

Last Update 25 Aug 26
Fair value Increased 2.61%MKS: Higher P E Assumptions And Execution Will Drive Future Upside
Analysts have nudged their fair value estimate for Marks and Spencer Group higher to £4.42 from £4.31, supported by recent price target moves to £4.70 and £4.50 that reflect updated views on growth, margins and future P/E assumptions.
Analyst Commentary
Recent Street research on Marks and Spencer Group points to a generally constructive tone around the stock, with price targets now in the £4.50 to £4.70 range. These views centre on how earnings growth, margins and P/E assumptions could support the current valuation.
Bullish Takeaways
- Bullish analysts see room for Marks and Spencer Group to justify a higher P/E multiple, which underpins the latest price target revisions to £4.50 and £4.70.
- The clustered targets in a relatively tight range suggest a degree of confidence that current execution on earnings and margins can support fair value closer to the upper end of recent estimates.
- Supportive Street views signal that recent progress in the business model is regarded as durable enough to factor into forward-looking valuation work.
- The raised targets from large banks such as JPMorgan help anchor sentiment for investors who track institutional research when assessing risk and reward.
Bearish Takeaways
- Higher targets also raise the execution bar. Any setback in earnings delivery or margin resilience could put pressure on the P/E assumptions that now underpin fair value around £4.42.
- The upside implied by the latest targets is more limited once the share price moves closer to the £4.50 to £4.70 range. That can reduce the margin of safety for new buyers.
- Bearish analysts may question whether recent improvements are fully reflected in these updated numbers, which could cap further multiple expansion without clear new catalysts.
- With expectations reset higher, Marks and Spencer Group now has less room for disappointment on growth, pricing or cost control before investors reassess these valuation levels.
What’s in the News for Marks and Spencer Group
- PLAYin CHOC Limited products are now stocked in over 500 Marks & Spencer Foodhalls across the UK, with organic, vegan, allergen free JustChoc Boxes and Woodland Animals ToyChoc Boxes in 140 stores, using fully recyclable and compostable packaging. Source, PLAYin CHOC client announcement.
- Marks and Spencer Group opened a new store at Weymouth Gateway Retail Park, offering a full Foodhall with Select Farm produce, bakery, coffee counter, hot chicken counter and dedicated gluten free and organic sections, alongside Flowers, Wine and a broad frozen and household range. Source, company business expansion announcement.
- The Weymouth Gateway store also brings an expanded Fashion offer, including Goodmove, Per Una, denim, lingerie such as Rosie Lingerie and menswear lines like the Autograph Pure Supima Cotton Performance Crew Neck T shirt, with a Click & Collect point for online fashion, home and beauty orders and over 70 new jobs created. Source, company business expansion announcement.
- Marks and Spencer Group extended its Amazon partnership to the Netherlands through an M&S Brand Store on Amazon.nl, with over 1,000 Womenswear, Menswear and Kidswear products, using Amazon fulfilment and offering next day delivery with free delivery for Amazon Prime members. Source, company client announcement.
- The company hosted a Capital Markets Day, giving investors and analysts a dedicated forum to hear management’s latest updates and priorities. Source, analyst and investor event listing.
Valuation Changes for Marks and Spencer Group
- Fair Value was nudged higher from £4.31 to £4.42, which is a small upward adjustment to the central estimate.
- The Discount Rate moved slightly higher from 7.89% to 8.06%, which points to a modestly higher required return in the model.
- Revenue Growth was assumed at 6.31% previously and is now set at 6.35%, which is a very small change in top line expectations.
- The Net Profit Margin was adjusted from 3.62% to 3.59%, which is a fractional reduction in the margin input.
- The Future P/E moved from 15.28x to 15.86x, which indicates a slightly higher valuation multiple being used for Marks and Spencer Group in the updated work.
Key Takeaways
- Strategic store expansion and digital investment could boost revenue through improved retail presence and increased online sales.
- Supply chain modernization and cost reduction efforts aim to enhance net margins and overall earnings.
- Significant challenges across international segments, digital investment pressures, and delayed infrastructure upgrades may hinder profitability and margin growth.
Catalysts
About Marks and Spencer Group- Operates various retail stores.
- Marks & Spencer’s focus on store rotation and acquiring new sites in high-growth locations indicates a future increase in revenue potential from improved retail presence and customer reach.
- The strategic investment in digital and technology initiatives is expected to enhance the online shopping experience, increasing digital sales and potentially raising overall revenue from the online segment.
- The company's plan to modernize its supply chain aims to create lower-cost and faster operations, which could enhance net margins through increased efficiency and reduced operational costs.
- Ongoing international business resets and leadership strengthening are expected to stabilize overseas performance, potentially reversing current declines and contributing to future revenue growth.
- The structural cost reduction program targeting £500 million savings by FY '28 should lower operational expenses, thereby improving net margins and enhancing overall earnings.
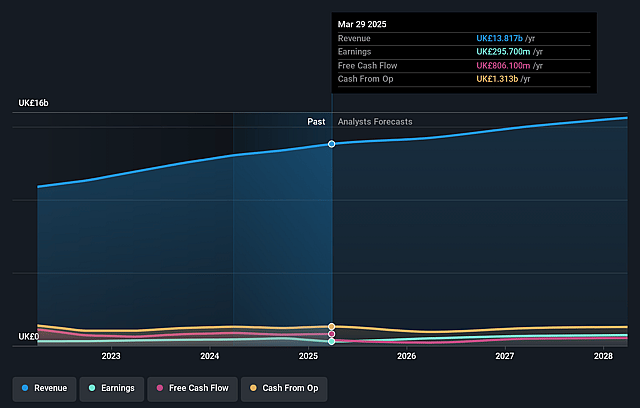
Marks and Spencer Group Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Marks and Spencer Group's revenue will grow by 6.4% annually over the next 3 years.
- Analysts assume that profit margins will increase from 1.5% today to 3.6% in 3 years time.
- Analysts expect earnings to reach £747.0 million (and earnings per share of £0.34) by about August 2029, up from £259.4 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as £831.5 million.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 15.9x on those 2029 earnings, down from 31.2x today. This future PE is lower than the current PE for the GB Consumer Retailing industry at 17.7x.
- Analysts expect the number of shares outstanding to grow by 1.09% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 8.06%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- The International business showed a disappointing performance, with sales down 10% and a reduced operating profit margin, which could negatively impact global revenues and margin growth.
- The Clothing & Home segment experienced increased operating costs as a percentage of sales due to lower online margins, which could pressure overall earnings despite store margin gains.
- The reset actions in International and increased investment requirements to improve digital and technology infrastructure suggest continued higher expenses, potentially impacting net margins.
- Ocado Retail, while showing growth, continues to operate at a loss, constraining overall group profitability and indicating risks to future earnings from this partnership.
- Store rotation and infrastructure upgrades have not progressed as quickly as planned, which may prolong cost pressures and affect potential returns on capital, impacting future profitability.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of £4.42 for Marks and Spencer Group based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of £5.0, and the most bearish reporting a price target of just £3.6.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be £20.8 billion, earnings will come to £747.0 million, and it would be trading on a PE ratio of 15.9x, assuming you use a discount rate of 8.1%.
- Given the current share price of £3.91, the analyst price target of £4.42 is 11.6% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Marks and Spencer Group?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.