
Last Update 24 Jul 26
Fair value Increased 2.98%IBE: Neutral Outlook As Network Expansion And Data Center Demand Shape Returns
The analyst price target for Iberdrola has been adjusted modestly higher to reflect a fair value shift of about €0.60 per share, as analysts cite mixed ratings but generally higher price targets linked to previously communicated earnings growth expectations and electricity demand in key markets.
Analyst Commentary
Recent research on Iberdrola points to a mixed but generally constructive tone, with several firms adjusting ratings and price targets as they reassess the stock's valuation against earnings expectations and electricity demand trends.
Bullish Takeaways
- Bullish analysts highlight Iberdrola's exposure to rising electricity demand in the U.S. and the UK as a key support for the growth outlook and, by extension, current valuation levels.
- Some price targets around €22 to €22.60 reflect confidence that Iberdrola can support a higher fair value range if it delivers on its earnings growth plans tied to power demand and data center related needs.
- Upgrades to more positive ratings are framed around the view that Iberdrola offers "superior" earnings growth potential compared with parts of the utilities sector. These analysts see this as a reason to justify a premium valuation.
- The clustering of price targets above €21 suggests that, for bullish analysts, Iberdrola's execution on growth projects remains central to their constructive stance on the stock's long term potential.
Bearish Takeaways
- Bearish analysts point to Iberdrola trading at a near 30% premium to the STOXX Europe 600 Utilities Index, and argue that this premium can only be justified if the company consistently delivers on earnings growth.
- Recent downgrades to more neutral ratings signal caution that expectations may already be demanding, leaving less room for error in execution and regulatory or demand outcomes.
- Some research commentary frames the current valuation as sensitive to any slowdown or shortfall versus earnings expectations, which could pressure the share price if growth or demand trends soften.
- The presence of both upgrades and downgrades in a short span underscores that not all analysts are aligned on Iberdrola's risk reward profile at current prices. The more cautious camp is focused on the high starting valuation and execution risks.
What’s in the News for Iberdrola
- Iberdrola has agreed to acquire an 80% stake in Caruna, Finland's largest electricity distribution network, aligning with its focus on electricity networks in markets with established regulatory regimes, according to recent news reports.
- The Caruna transaction is targeted to close in the first quarter of 2027, subject to regulatory approvals, which adds a longer dated element for investors to track around Iberdrola’s network footprint in Northern Europe. (Source: Caruna acquisition coverage)
- Iberdrola reported 6.3% growth in electricity distribution, supported by expanded wind and solar capacity in the first half of 2026, with the United Kingdom showing a 32.6% rise in distribution volume. (Source: Iberdrola H1 2026 distribution update)
- The company plans to invest about €21b through 2028 in renewable projects, smart grids, battery storage, and decarbonization solutions, linking current operations to longer term energy transition plans. (Source: Iberdrola H1 2026 distribution update)
- A stock split or significant stock dividend is scheduled with a 1 : 2.89126 ratio dated Jul 06 2026, which may affect Iberdrola’s share count and per share trading price once effective. (Source: company key developments)
Valuation Changes for Iberdrola
- Fair Value: updated modestly higher from €19.92 to €20.52, a change of about 3.0%.
- Discount Rate: kept unchanged at 7.32%, indicating no adjustment to the risk assumption used in the valuation work.
- Revenue Growth: revised slightly higher from 4.00% to 4.12%, a change of about 0.12 percentage points.
- Net Profit Margin: adjusted marginally upward from 15.74% to 15.77%, a change of about 0.03 percentage points.
- Future P/E: reported at 25.0x on the updated figures, reflecting the valuation multiple applied to Iberdrola’s earnings.
Key Takeaways
- Expansion of regulated network assets and clean energy projects, backed by supportive policies, drives predictable revenue growth and higher margins.
- Strong financing and operational cash flow support ambitious investments, maintaining reliable dividends and reducing the need for new equity.
- Heavy reliance on regulated markets, partnership funding, and favorable regulation exposes Iberdrola to political, financial, and execution risks that threaten profitability and growth targets.
Catalysts
About Iberdrola- Engages in the generation, production, transmission, distribution, and supply of electricity in Spain, the United Kingdom, the United States, Mexico, Brazil, Germany, France, and Australia.
- Major expansion of regulated network investments in the US and UK, supported by stable and attractive policy frameworks and recently approved regulatory determinations, is expected to nearly triple Iberdrola's regulated asset base to €90bn by 2031. This should drive sustained, predictable growth in revenues and a structural increase in regulated net margins.
- Ongoing acceleration of grid modernization and digitalization-driven by enhanced incentives in the new regulatory regimes-will improve operational efficiency, reduce network losses, and boost EBITDA margins over time as these investments scale across core regions.
- A multi-year pipeline of large offshore wind and renewable projects in the US, UK, and continental Europe, backed by supportive government policies and long-term power purchase agreements, underpins forward-looking growth in clean generation capacity and future revenues.
- The electrification of transport, heating, and industrial sectors in both Europe and the US is expected to steadily raise electricity demand over the next decade, expanding Iberdrola's addressable market and enhancing long-term top-line and EBITDA growth prospects.
- Growing access to green finance, along with robust operational cash flow and a successful equity raise, ensures Iberdrola can fund its ambitious expansion with comfortable leverage and no need for additional equity until at least 2030, supporting sustained investment, future earnings growth, and reliability of dividend policies.
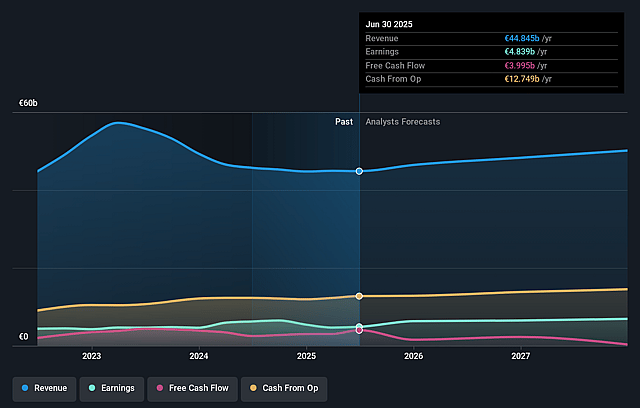
Iberdrola Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Iberdrola's revenue will grow by 4.1% annually over the next 3 years.
- Analysts assume that profit margins will increase from 12.5% today to 15.8% in 3 years time.
- Analysts expect earnings to reach €7.9 billion (and earnings per share of €1.18) by about July 2029, up from €5.6 billion today. The analysts are largely in agreement about this estimate.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 25.0x on those 2029 earnings, up from 24.7x today. This future PE is greater than the current PE for the GB Electric Utilities industry at 17.8x.
- Analysts expect the number of shares outstanding to grow by 4.93% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 7.32%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Iberdrola's significant reliance on regulated markets-particularly in the U.K. and the U.S., which will account for approximately 75% of the regulated asset base by 2031-increases exposure to potential adverse changes in regulatory frameworks or political intervention, which could negatively impact allowed returns, pricing power, and future net margins.
- The company is undertaking a large €5 billion equity raise to fund an unprecedented acceleration in network investments, indicating heavy dependence on favorable capital market conditions and access to green financing; should macroeconomic conditions shift (e.g., rising interest rates or tighter credit), Iberdrola may face higher financing costs, pressuring future profitability and earnings growth.
- While Iberdrola's focus shifts to networks, growth in renewables investment is largely being maintained only through asset rotation and co-investment strategies; heavy reliance on these partnership and asset sale mechanisms to fund growth could expose the company to execution risk, dilution of returns, or subdued revenue growth if market appetite weakens or partners become scarce.
- Spanish regulatory uncertainty, as highlighted by ongoing concerns regarding investment caps, slow recognition of investment, and unfavorable draft proposals for network remuneration, suggests downside risks for Iberdrola's domestic regulated business, with potential impacts on revenue growth, cost recovery, and regional net margins.
- The group's rapidly expanding asset base and leverage (despite improved ratios post-asset rotation) could become a long-term financial risk if regulatory returns fail to keep pace with cost inflation, future rate hikes, or if investments face delays and overruns-collectively jeopardizing targets for EBITDA growth, net profit, and dividend sustainability.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of €20.52 for Iberdrola based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of €23.8, and the most bearish reporting a price target of just €17.3.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be €50.2 billion, earnings will come to €7.9 billion, and it would be trading on a PE ratio of 25.0x, assuming you use a discount rate of 7.3%.
- Given the current share price of €21.21, the analyst price target of €20.52 is 3.4% lower. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Iberdrola?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Regulated Networks And Offshore Wind Expansion Will Support A Stronger Long Term Outlook
View narrative
Offshore Wind Risks And Grid Constraints Will Pressure Returns Over The Coming Years
View narrative