
Last Update 23 Jun 26
Fair value Decreased 0.64%BRBY: Recent Pullback And 2027 Guidance Will Support Future Bullish Thesis
The analyst price target for Burberry Group has been trimmed by £0.10 to £15.60, as analysts weigh recent share price moves, updated growth and margin assumptions, and a mix of cautious and positive broker views on the stock.
Analyst Commentary
Recent research on Burberry Group reflects a wide spread of views, with bullish analysts highlighting potential upside after the recent share pullback and others staying more cautious on execution and the macro backdrop. Across the reports, investors are being asked to weigh differing opinions on where the stock currently sits in its repositioning cycle and how that lines up with valuation.
On the more constructive side, one large global bank upgraded Burberry to an Overweight rating with a price target of £13.50, pointing to the recent share price pullback as a possible entry point. Another bullish analyst trimmed a target slightly to £15.60 but maintained a positive stance on the stock, while JPMorgan lifted its target to £9.80 and kept an Underweight rating, indicating that even more cautious firms are revisiting their assumptions.
There are still neutral voices in the mix. One firm initiated coverage with a neutral view, and another kept a Market Perform rating while edging its target to £13.00 and emphasising that Burberry is still early in its global repositioning. A separate bank also lowered its target by £0.70, highlighting that execution and macro conditions remain key watchpoints for investors.
Bullish Takeaways
- Bullish analysts argue that the recent share price pullback has opened up a potential entry point for investors who are comfortable with Burberry Group's ongoing repositioning story.
- The presence of price targets clustered around and above £13.00, even where ratings differ, suggests that several firms continue to see room for upside relative to current trading levels.
- Upbeat commentary on "solid" Q4 comparable performance and perceived improvement in revenue quality supports the view that Burberry's underlying brand and product execution are moving in a constructive direction.
- The mix of an Overweight rating from a major global bank alongside a Buy rating elsewhere provides investors with supportive reference points if Burberry continues to deliver on its repositioning and margin ambitions.
What’s in the News for Burberry Group
- Burberry Group issued earnings guidance for fiscal 2027, indicating that it expects to make further progress on its financial ambitions, including revenue growth and margin expansion. [Source: Key Developments]
- The fiscal 2027 guidance keeps Burberry Group’s medium term financial goals in focus, with management describing both revenue and margin outcomes as key markers for that period. [Source: Key Developments]
- The company’s outlook statement for fiscal 2027 provides investors with a reference point for assessing how future updates align with Burberry Group’s stated ambitions on growth and profitability. [Source: Key Developments]
Valuation Changes for Burberry Group
- Fair Value: trimmed slightly from £15.70 to £15.60, reflecting a modest adjustment to the analyst model.
- Discount Rate: raised from 10.02% to 10.17%, implying a slightly higher required return being applied to Burberry Group's cash flows.
- Revenue Growth: assumption adjusted from 7.12% to 7.52%, signalling a small uplift in expected top line growth for Burberry Group in the model.
- Net Profit Margin: brought down from 11.83% to 11.50%, indicating a slightly more cautious view on future profitability.
- Future P/E: eased from 21.76x to 21.41x, suggesting a marginally lower valuation multiple being used for Burberry Group's earnings outlook.
Key Takeaways
- Burberry's brand elevation, digital acceleration, and unique market positioning are driving faster-than-expected revenue, margin, and customer growth versus industry expectations.
- Focus on sustainability and ESG, plus innovative, data-driven merchandising, is enhancing pricing power, retention, and long-term global market share.
- Heavy reliance on traditional branding, shrinking wholesale business, and slow digital adaptation threaten Burberry's revenue growth, market share, and ability to appeal to new consumer segments.
Catalysts
About Burberry Group- Engages in manufacturing, retail, and wholesale of luxury goods under the Burberry brand in the Asia Pacific, Europe, the Middle East, India, Africa, and the Americas.
- Analyst consensus expects Burberry's brand elevation to drive top-line growth and higher average selling prices, but the current momentum in brand affinity and rapid conversion of runway desirability into commercial success suggests Burberry could return to £3 billion in revenue and 70% gross margin significantly sooner, with upside from rapid sellouts and organic scarcity, directly lifting revenue and margin recovery above expectations.
- Whereas analyst consensus sees digital and omnichannel investments restoring e-commerce growth and boosting margin, early evidence of reaccelerating digital sales and data-driven merchandise optimization points to a step-change in revenue per customer and store productivity, implying faster-than-expected net margin and earnings expansion through both operating leverage and fixed cost absorption.
- The ongoing global democratization of wealth, especially in Asia-Pacific and among younger, digitally savvy luxury buyers, creates a powerful, underappreciated demand tailwind for Burberry's newly sharpened, authentically British brand proposition, positioning the company to achieve outpaced growth versus peers and drive a structural uplift in both international revenues and long-term market share.
- Burberry is uniquely positioned to monetize growing consumer demand for ethical and sustainable luxury, with scalable in-store circularity initiatives and a deepened commitment to UK manufacturing enhancing pricing power, capturing share from ESG-oriented customers, and supporting both gross margin and brand goodwill over time.
- The unprecedented alignment of design, merchandising, and data-led commercial teams is generating product innovation and customer-centric execution at a pace rarely seen in legacy luxury houses, likely leading to accelerated new customer acquisition, higher retention, and a meaningful step up in direct-to-consumer earnings and free cash flow.
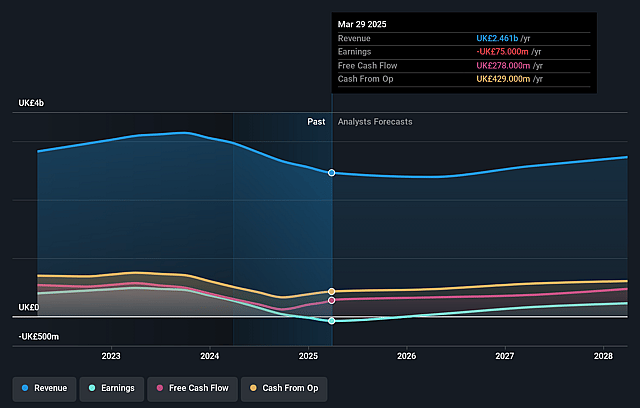
Burberry Group Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- This narrative explores a more optimistic perspective on Burberry Group compared to the consensus, based on a Fair Value that aligns with the bullish cohort of analysts.
- The bullish analysts are assuming Burberry Group's revenue will grow by 7.5% annually over the next 3 years.
- The bullish analysts assume that profit margins will increase from 0.9% today to 11.5% in 3 years time.
- The bullish analysts expect earnings to reach £345.8 million (and earnings per share of £0.96) by about June 2029, up from £21.0 million today. However, there is some disagreement amongst the analysts with the more bearish ones expecting earnings as low as £206.6 million.
- In order for the above numbers to justify the price target of the more bullish analyst cohort, the company would need to trade at a PE ratio of 21.4x on those 2029 earnings, down from 188.1x today. This future PE is lower than the current PE for the GB Luxury industry at 28.5x.
- The bullish analysts expect the number of shares outstanding to decline by 0.27% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 10.17%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Burberry is facing a structural decline in wholesale revenue, which fell 35% year-on-year, and ongoing cuts to wholesale partners and door closures in Europe are expected to weigh on revenue growth and limit global expansion over the medium term.
- Demographic shifts and changing consumer preferences, particularly among millennials and Gen Z who are less drawn to heritage brands, place Burberry's reliance on classic "Timeless British Luxury" at risk and could result in lower demand and reduced sales growth.
- Geopolitical uncertainties and trade tensions, especially potential tariffs and ongoing volatility in key regions like China and the U.S., threaten to disrupt Burberry's international footprint and introduce unpredictable impacts on revenue and operating margins.
- There is ongoing risk of brand dilution and inconsistent product elevation, with the company still in the early stages of its turnaround and no full proof that recent initiatives will restore pricing power and gross margin to historic highs, creating downside risk to earnings targets.
- Despite initial improvements, Burberry's slow digital transformation and continued focus on physical retail-including the maintenance of a large global store network-raise concerns about its ability to keep pace with luxury industry trends toward omni-channel retailing, thereby risking both revenue growth and market share.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The assumed bullish price target for Burberry Group is £15.6, which represents up to two standard deviations above the consensus price target of £12.99. This valuation is based on what can be assumed as the expectations of Burberry Group's future earnings growth, profit margins and other risk factors from analysts on the bullish end of the spectrum.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of £15.6, and the most bearish reporting a price target of just £9.4.
- In order for you to agree with the more bullish analyst cohort, you'd need to believe that by 2029, revenues will be £3.0 billion, earnings will come to £345.8 million, and it would be trading on a PE ratio of 21.4x, assuming you use a discount rate of 10.2%.
- Given the current share price of £11.03, the analyst price target of £15.6 is 29.3% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Burberry Group?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystHighTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystHighTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystHighTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Digital Trends Will Undermine Legacy Retail While Cost Cuts Help
View narrative
Analyst Commentary Signals Shifting Sentiment and Raised Price Targets for Burberry Group
View narrative