
Last Update 15 Sep 26
Fair value Increased 11%VLE: Faster Gulf Redevelopment And Leaner Margins Will Shape Future Returns
Analysts have raised their price target for Valeura Energy from CA$14.00 to CA$15.50, citing updated assumptions on revenue trends, profit margins, and the future P/E multiple.
What's in the News for Valeura Energy
- Valeura Energy plans to accelerate redevelopment of the Wassana field in the Gulf of Thailand, with the new central processing platform construction ahead of schedule and installation targeted to start in October 2026, according to recent company announcements and news reports.
- The accelerated Wassana timeline is expected to shift some planned spending into 2026, with updated adjusted capex guidance of US$220 million to US$235 million for the year, compared with the previous range of US$195 million to US$215 million. Source: company guidance.
- Valeura Energy is targeting a production plateau of about 7,500 bbls/d from the new Wassana platform and has indicated that a two-month earlier start-up could add approximately 430,000 barrels of oil in 2027 versus the prior plan. Source: company announcement.
- The company completed an eight-well drilling campaign at the Nong Yao field in the Gulf of Thailand, including its first multilateral development well and what it reports as the longest horizontal lateral drilled in the Gulf of Thailand at 4,960 feet. Source: company operational update.
- For Q2 2026, Valeura Energy reported average oil production of 22.3 mbbls/d and is maintaining 2026 production guidance of 20,000 bbls/d to 22,000 bbls/d. Source: company results and guidance release.
Valuation Changes for Valeura Energy
- Fair Value has risen from CA$14.00 to CA$15.50, which is a modest upward revision in the valuation estimate for Valeura Energy.
- Discount Rate is essentially unchanged at 6.44%, indicating no material shift in the risk assumption used in the valuation model.
- Revenue Growth expectations have improved slightly, with the projected annual change revised from a decline of 4.45% to a smaller decline of 3.63%.
- Net Profit Margin assumptions have fallen significantly, moving from 18.00% to 5.78%, which represents a much leaner earnings outlook on each $ of revenue.
- Future P/E has risen sharply from 12.15x to 40.86x, which points to a much higher valuation multiple being applied to Valeura Energy in the new model.
Key Takeaways
- Reliance on Southeast Asian assets and fossil fuels exposes Valeura to regulatory, political, and decarbonization risks, threatening future earnings and capital access.
- Operational strengths and reserve additions may not offset headwinds from ESG regulation, shrinking demand, and declining long-term profitability in the oil and gas sector.
- Heavy reliance on offshore Thailand oil assets exposes Valeura to significant geographic, regulatory, and industry risks that may threaten earnings stability and long-term growth.
Catalysts
About Valeura Energy- Engages in the exploration, development, and production of petroleum and natural gas in Thailand and in Turkey.
- While Valeura Energy has delivered strong reserve replacement and successful field extensions in its Thailand offshore assets, the company remains heavily exposed to the risk of accelerating global decarbonization policies and the rise of renewables, which could erode long-term demand for oil and gas and weigh on future revenue growth.
- Despite the company's efficiency gains and robust operating cash flow supported by lower OpEx and tax optimization, persistent uncertainties around stricter ESG-driven regulation and potential carbon pricing could significantly raise operating costs and reduce net margins going forward.
- Although substantial reserves have been added and field life has been extended well into the 2030s, ongoing geographic concentration in Southeast Asia exposes Valeura to political or regulatory changes that may negatively impact earnings, especially if local fiscal regimes become less favourable.
- While the energy sector is seeing strengthened commodity price support due to global underinvestment in upstream capacity, Valeura faces long-term reserve replacement risks: continued strong performance in infill drilling and resource conversion may not be indefinitely sustainable, which could ultimately pressure future top-line revenue and profitability.
- Even as the company leverages its sizeable cash position and low leverage to fund organic development and potential M&A, the structural trend of global capital flows away from fossil fuels could constrain access to low-cost capital and limit shareholder returns, dampening the outlook for future dividends or buybacks.
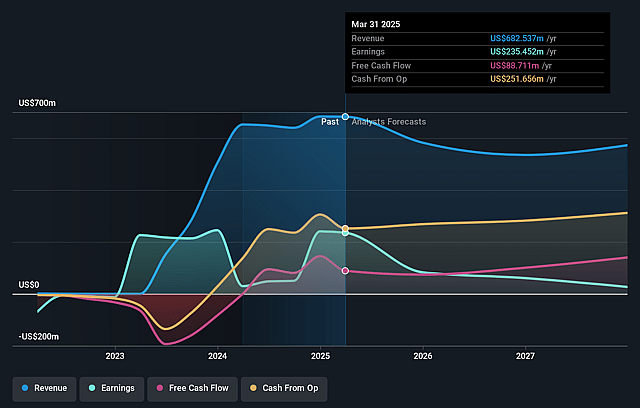
Valeura Energy Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- This narrative explores a more pessimistic perspective on Valeura Energy compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts.
- The bearish analysts are assuming Valeura Energy's revenue will decrease by 3.6% annually over the next 3 years.
- The bearish analysts assume that profit margins will shrink from 9.2% today to 5.8% in 3 years time.
- The bearish analysts expect earnings to reach $34.8 million (and earnings per share of $0.31) by about September 2029, down from $62.3 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as $161.2 million.
- In order for the above numbers to justify the price target of the more bearish analyst cohort, the company would need to trade at a PE ratio of 41.1x on those 2029 earnings, up from 18.8x today. This future PE is greater than the current PE for the CA Oil and Gas industry at 21.0x.
- The bearish analysts expect the number of shares outstanding to grow by 0.15% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 6.44%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Valeura Energy is heavily reliant on its offshore Thailand oil assets, which creates geographic concentration risk; any adverse changes in the regulatory, fiscal, or political landscape in Thailand could disrupt operations, impacting future revenues and earnings stability.
- The company's recent reserve growth and field life extensions are largely dependent on continued infill drilling and successful appraisal results; a slowdown in exploration success, inability to replenish reserves, or earlier-than-expected field declines could erode long-term production levels and reduce earnings.
- Structural headwinds for oil due to global decarbonization policies and rapid uptake of renewable energy pose a risk to long-term oil demand, potentially placing downward pressure on realized oil prices and constraining Valeura's ability to sustain its margins and cash flow into the 2030s.
- Intensifying ESG regulations and anticipated increases in carbon pricing could drive higher operating costs for Valeura, directly lowering future net margins and potentially reducing access to low-cost capital needed for project expansions.
- Valeura's growth narrative is supported by aggressive expansion plans and potential M&A activity, which carry execution risks; integration missteps or acquisition of non-accretive assets could lead to increased financial leverage, lower returns on capital, and diminished shareholder value reflected in future net income.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The assumed bearish price target for Valeura Energy is CA$15.5, which represents up to two standard deviations below the consensus price target of CA$17.74. This valuation is based on what can be assumed as the expectations of Valeura Energy's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of CA$21.0, and the most bearish reporting a price target of just CA$15.5.
- In order for you to agree with the more bearish analyst cohort, you'd need to believe that by 2029, revenues will be $602.8 million, earnings will come to $34.8 million, and it would be trading on a PE ratio of 41.1x, assuming you use a discount rate of 6.4%.
- Given the current share price of CA$15.32, the analyst price target of CA$15.5 is 1.2% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Valeura Energy?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystLowTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystLowTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystLowTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Southeast Asia Oil Expansion Will Spur Production Amid Transition Risks
View narrative
Wassana Redevelopment Will Define Future Prospects Despite Risks
View narrative