
Last Update 21 Aug 26
Fair value Increased 3.11%6963: Power Chip Upside Will Track Lengthy AI Semiconductor Cycle
Analysts have lifted their fair value estimate for ROHM from ¥5,590 to about ¥5,764, citing updated revenue, margin and P/E assumptions, along with a higher Street price target of ¥6,500 tied to expectations for a lengthy semiconductor upcycle.
What's in the News for ROHM
- ROHM issued consolidated earnings guidance for the year ending 31 March 2027. The company expects net sales of ¥510,000 million, operating profit of ¥30,000 million, profit attributable to owners of parent of ¥29,000 million, and net income per share of ¥75.12. [Source: Corporate guidance]
- ROHM Semiconductor introduced a 2nd generation terahertz wave oscillation device using Resonant Tunneling Diodes, offered through the RTD-EVK-G2 evaluation kit. The device maintains a 0.5 × 0.5 mm chip size and is described as delivering approximately 4x higher output power than the prior generation, with planned kit sales starting in August 2026. [Source: Product announcement]
- The company released the BD83070GWL-EVK-002 evaluation board for its BD83070GWL buck boost DC-DC converter IC. The solution targets compact, battery powered devices such as wearables, mobile devices, IoT nodes, and other small electronics. [Source: Product announcement]
- ROHM launched new 600V Super Junction MOSFET series R60xxXNx and R60xxWNx, adding compact DFN8080 5L and TOLL surface mount packages aimed at data center and industrial power supplies, motors, inverters, and consumer equipment. [Source: Product announcement]
- The board of ROHM met on 24 June 2026 to consider and approve disposal of treasury shares under a performance share restricted stock unit compensation plan. [Source: Board meeting disclosure]
Valuation Changes for ROHM
- Fair value was updated from ¥5,590 to about ¥5,764, which represents a small upward adjustment of around 3%.
- The discount rate moved from 10.37% to about 10.61%, a modest increase that slightly raises the hurdle rate applied to ROHM.
- Revenue growth was adjusted from about 7.09% to about 6.96%, a small reduction in the assumed long term growth rate.
- Net profit margin was refined from about 12.24% to about 12.85%, indicating a slightly higher profitability assumption for ROHM.
- Future P/E moved from about 40.1x to about 38.3x, a small reduction in the multiple applied to the company’s earnings outlook.
Key Takeaways
- Expansion in SiC power devices and optimized investment aims to boost revenue, align with market demand, and improve returns.
- Strategic partnerships and organizational restructuring target enhanced sales, better customer alignment, and increased profitability through cost reductions and improved efficiencies.
- The company faces revenue challenges due to declines in industrial and automotive segments, inventory issues, and unachieved cost reductions impacting profitability.
Catalysts
About ROHM- Manufactures and sells electronic components worldwide.
- ROHM is planning to increase its production capacity and efficiency for SiC (silicon carbide) power devices, correlating with expected battery EV market growth, which should enhance revenue and earnings as demand eventually picks up.
- The company is implementing a new organizational structure to better cater to customer needs and market applications, which aims to improve sales and potentially increase net margins by offering more integrated, solution-based proposals.
- Significant cost reduction measures are being implemented, including a plan to decrease annual fixed costs by ¥20 to 30 billion over the next three years and increased outsourcing, which is expected to improve net margins and profitability.
- ROHM is deferring certain capital expenditures and optimizing investment efficiency, aiming to align investments with demand trends, which should stabilize earnings and improve return on investment as market conditions improve.
- Strategic partnerships, such as with DENSO and potential alliances with Toshiba, are poised to enhance collaborative opportunities and could lead to steady revenue increases and strengthen competitive positioning in the semiconductor market.
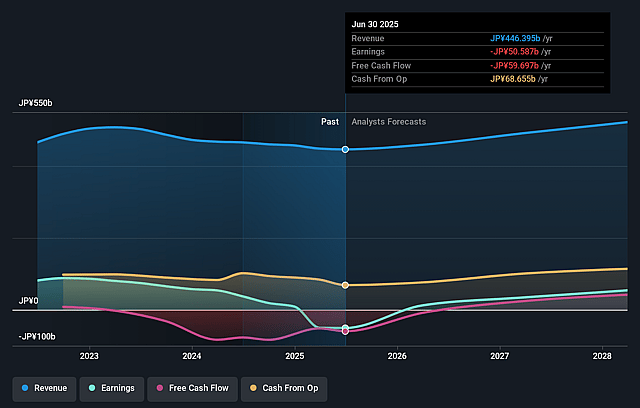
ROHM Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming ROHM's revenue will grow by 7.0% annually over the next 3 years.
- Analysts assume that profit margins will increase from -30.4% today to 12.8% in 3 years time.
- Analysts expect earnings to reach ¥78.7 billion (and earnings per share of ¥196.49) by about August 2029, up from -¥152.4 billion today. However, there is a considerable amount of disagreement amongst the analysts with the most bullish expecting ¥145.0 billion in earnings, and the most bearish expecting ¥70.7 billion.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 38.3x on those 2029 earnings, up from -11.9x today. This future PE is greater than the current PE for the JP Semiconductor industry at 21.1x.
- Analysts expect the number of shares outstanding to remain consistent over the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 10.61%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- A significant decline in the industrial market segment, with a year-on-year drop of 28.1%, continues due to ongoing inventory adjustments, impacting overall revenue prospects.
- The operating profit turned negative due to a combination of inventory impacts and increased fixed expenses, which are not being offset by the expected cost reduction measures, affecting net margins and earnings.
- The downward revision of net sales and operating profit forecasts, with an operating loss expected, underscores challenges in meeting initial financial targets and managing expenses effectively, impacting earnings and profitability.
- A slowdown in the battery EV market, particularly in China, limits the growth potential for SiC power devices, which are critical for future revenue growth in the automotive sector.
- The continued dependency and exposure to declines in the Japanese automotive and industrial market segments, coupled with a weak sales forecast, could lead to lower revenue stability and financial stress.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of ¥5763.64 for ROHM based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of ¥8300.0, and the most bearish reporting a price target of just ¥3500.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be ¥612.6 billion, earnings will come to ¥78.7 billion, and it would be trading on a PE ratio of 38.3x, assuming you use a discount rate of 10.6%.
- Given the current share price of ¥4699.0, the analyst price target of ¥5763.64 is 18.5% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on ROHM?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

SiC Expansion And Margin Targets Will Likely Strain Capacity And Depress Returns
View narrative
Fair Long-Term View Centers On SiC Power Devices And Automotive Expansion
View narrative