
Last Update 14 Aug 26
Fair value Decreased 7.49%NETC: Share Buyback And Lower P E Expectations Will Shape Returns
Netcompany Group's analyst fair value has been revised lower from DKK 334 to DKK 309, as analysts factor in updated assumptions on discount rates, revenue growth, profit margins and future P/E expectations, alongside recent downward adjustments to Street price targets.
Analyst Commentary
Recent Street updates on Netcompany Group show a series of lower price targets, which points to a more cautious stance from several bearish analysts. The latest revisions cluster in a relatively narrow DKK range, which suggests that concerns are focused on the balance between growth expectations, execution risks and what investors are currently willing to pay on a P/E basis.
Across these reports, bearish analysts have trimmed their fair value views multiple times over recent months. The current analyst fair value of DKK 309 sits at the lower end of these updated targets, which places extra attention on how Netcompany Group delivers against upcoming revenue and margin expectations.
Bearish Takeaways
- Bearish analysts are cutting price targets from prior levels up to DKK 380 toward a tighter band of DKK 309 to DKK 370, which signals reduced confidence in the previous upside case for Netcompany Group.
- The latest DKK 309 target from a major broker aligns closely with the revised analyst fair value, which highlights concern that valuation may already reflect execution and growth challenges.
- Neutral and Underweight ratings around these lower targets point to reservations about Netcompany Group’s ability to justify higher P/E multiples without clearer evidence on revenue growth and profit margins.
- Repeated downward adjustments over time, including the more recent move to DKK 350 from DKK 370, show that bearish analysts are wary of potential upside surprises and prefer to stay cautious on risk and reward for now.
What’s in the News for Netcompany Group
- Netcompany Group reported Q2 2026 organic revenue growth of 17.3% and total reported revenue growth of 43.3%, supported by its Netcompany Banking Services division. Source: Recent earnings coverage.
- On the back of first half 2026 revenue growth of 40.9%, Netcompany Group raised full year 2026 revenue growth guidance to 16% to 20.5%, compared with the previous range of 15% to 20%. Source: Company guidance updates.
- The company kept its adjusted EBITDA margin guidance unchanged for 2026, even as revenue guidance moved higher. Source: Company guidance updates.
- Management highlighted faster adoption of AI technologies and strong market performance in the UK, and is continuing to invest in AI driven digital solutions for European governments and enterprises. Source: Recent earnings coverage.
- Netcompany Group launched a DKK 750 million share buyback programme, allowing the repurchase of up to 3,250,000 shares between 3 February 2026 and 29 January 2027, in part to manage its capital structure and share based incentive schemes. All trades will be reported weekly via Nasdaq Copenhagen. Source: Company announcement.
Valuation Changes for Netcompany Group
- Fair Value has been revised from DKK 334.0 to DKK 309.0, which reflects a moderate reduction in the analyst fair value estimate for Netcompany Group.
- Discount Rate has moved from 7.72% to 8.27%, which indicates a slightly higher required return in the updated model.
- Revenue Growth has shifted from 7.90% to 5.95%, which points to more cautious assumptions on future DKK revenue expansion.
- Net Profit Margin has been adjusted from 11.01% to 10.70%, which signals a small reduction in expected profitability on future DKK earnings.
- Future P/E has changed from 14.10x to 12.59x, which suggests a lower assumed valuation multiple for Netcompany Group in the updated forecasts.
Catalysts
About Netcompany Group
Netcompany Group delivers IT services, platforms and AI enabled digital solutions for public and private sector clients, primarily in Europe.
What are the underlying business or industry changes driving this perspective?
- The heavy push into AI based platforms such as VERÁ, AMPLIO Estate and AMPLIO Life and Pension relies on continued large scale digitisation projects by governments and enterprises. Any slowdown in adoption of these complex systems could limit new contracts and weigh on revenue growth and license income.
- European digital sovereignty and defense digitisation are still developing policy areas. If procurement for VERÁ and similar offerings is delayed or fragmented across countries, utilisation of these platforms may stay below current capacity and pressure margins.
- The integration of Netcompany Banking Services, including a large transformation program and restructuring through 2028, introduces execution risk. If cost savings arrive later or are smaller than planned, group EBITDA margins and earnings could remain below management ambitions for longer.
- The shift from capitalising around DKK 200 million of own developed software in the acquired banking unit to much lower IFRS based capitalization raises reported operating expenses. If price increases or volume growth do not offset this, reported profitability and earnings per share could be weaker than investors expect.
- Free cash flow in Q3 2025 was affected by working capital swings and negative contribution from Netcompany Banking Services. If large project milestone timing and integration cash costs continue to strain cash conversion, the group could have less flexibility for shareholder returns and future investments.
Assumptions
How have these above catalysts been quantified?
- This narrative explores a more pessimistic perspective on Netcompany Group compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts.
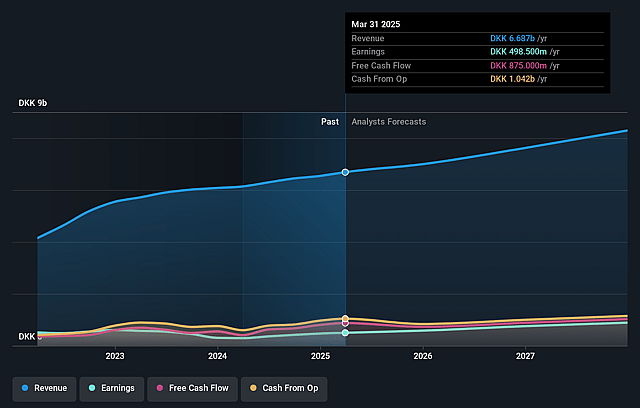
- The bearish analysts are assuming Netcompany Group's revenue will grow by 6.0% annually over the next 3 years.
- The bearish analysts assume that profit margins will increase from 4.5% today to 10.7% in 3 years time.
- The bearish analysts expect earnings to reach DKK 1.2 billion (and earnings per share of DKK 26.74) by about August 2029, up from DKK 420.0 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as DKK1.6 billion.
- In order for the above numbers to justify the price target of the more bearish analyst cohort, the company would need to trade at a PE ratio of 12.6x on those 2029 earnings, down from 35.9x today. This future PE is lower than the current PE for the DK IT industry at 52.3x.
- The bearish analysts expect the number of shares outstanding to decline by 5.19% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 8.27%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?
- Netcompany is positioning itself around AI ready platforms such as VERÁ, AMPLIO Estate and AMPLIO Life and Pension at a time when European governments and large enterprises are actively pursuing digital sovereignty and automation. If this long term push into European hosted digital infrastructure continues, it could provide a sustained source of contract wins that supports revenue and earnings.
- The company has reported organic revenue growth in both public and private segments across several geographies and is building a backlog and revenue visibility tied to long duration digitisation programs. If these secular digitisation trends in government services and regulated industries persist, they may underpin more resilient long term revenue than a bearish share price view assumes.
- Netcompany Banking Services, including the former SDC platform, sits in an industry where IT spend at banks has historically risen as services move from internal IT departments to specialised providers. Ongoing consolidation in Nordic banking could create further demand for modular, AI supported banking solutions that benefits group revenue and margins.
- The shift to product and platform based delivery, combined with disciplined use of offshore FTEs and cost synergies targeted from the SDC integration, gives management several operational levers that can support adjusted EBITDA margin over time. If license based income from vertical products grows on top of existing services, that may support net margins and earnings more than a bearish case builds in.
- Management has communicated long term targets for organic revenue growth and an adjusted EBITDA margin above 20% for the group including Netcompany Banking Services by 2029. If execution against these goals stays on track through continued contract wins and integration progress, the trajectory of earnings and cash generation could contradict expectations of a sustained share price decline.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The assumed bearish price target for Netcompany Group is DKK309.0, which represents up to two standard deviations below the consensus price target of DKK381.12. This valuation is based on what can be assumed as the expectations of Netcompany Group's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of DKK435.0, and the most bearish reporting a price target of just DKK309.0.
- In order for you to agree with the more bearish analyst cohort, you'd need to believe that by 2029, revenues will be DKK11.1 billion, earnings will come to DKK1.2 billion, and it would be trading on a PE ratio of 12.6x, assuming you use a discount rate of 8.3%.
- Given the current share price of DKK338.4, the analyst price target of DKK309.0 is 9.5% lower. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Netcompany Group?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystLowTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystLowTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystLowTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

NETC: Organic Revenue Range Adjustment And Profit Margin Outlook Will Balance Risks And Opportunities
View narrative