

Last Update 08 Aug 26
Fair value Increased 16%PRL: Rising Dividend And U S U K Expansion Plans Will Drive Re Rating
Analysts have lifted their fair value estimate for Propel Holdings to CA$35.11 from CA$30.36, reflecting higher Street price targets in the CA$29 to CA$38 range supported by expectations for sustained loan and earnings growth through 2027.
Analyst Commentary
Street research on Propel Holdings remains focused on how the company can execute on growth plans in both the U.S. and U.K., along with what that might mean for valuation over the next few years. Recent price target moves sit in the C$29 to C$38 range and give investors a sense of how bullish analysts are thinking about loan growth, earnings power, and returns on equity through 2027.
Bullish Takeaways
- Bullish analysts have lifted price targets from the high C$20s into the mid to high C$30s. This signals confidence that Propel Holdings can support a higher valuation if it stays on track with current plans.
- Coverage that started with a Buy rating and a C$33 target frames Propel Holdings as a sub prime fintech consumer lender with room to scale, especially given its current size relative to the markets it serves.
- There is emphasis on the opportunity to expand into additional U.S. states and build out the U.K. business. Bullish analysts see these areas as important engines for loan book growth and higher earnings over time.
- Some research points to the potential for strong loan and earnings growth along with solid ROE through 2027. This view underpins the upper end of the current target range around C$37 to C$38.
Bearish Takeaways
- One firm maintains a Sector Perform stance even after raising its target to C$29. This signals caution about how much upside is left from current levels compared with other financial stocks.
- Bearish analysts appear more measured on execution risk around U.S. state expansion and U.K. growth. These factors could affect how quickly Propel Holdings converts its opportunity set into sustained earnings.
- The spread between the lower and upper Street targets, from about C$29 to C$38, highlights ongoing debate about how reliably Propel Holdings can deliver on growth forecasts and maintain returns on equity.
- Investors are encouraged to weigh the higher price targets against the risk that loan growth, earnings growth, or ROE might track below the expectations that underpin bullish models.
What’s in the News for Propel Holdings
- Propel Holdings announced that its Board of Directors approved an increase in the quarterly dividend from C$0.24 per common share to C$0.255 per common share, which is C$0.96 to C$1.02 per common share on an annualized basis. This was described as a 6% increase and the twelfth consecutive quarterly dividend increase. Source, company announcement.
- The Board declared a quarterly dividend of C$0.255 per common share, payable on September 3, 2026, to shareholders of record as of the close of business on August 14, 2026. Source, company announcement.
- Propel Holdings designated this dividend as an eligible dividend for purposes of the Income Tax Act in Canada. Source, company announcement.
Valuation Changes for Propel Holdings
- Fair Value has risen from CA$30.36 to CA$35.11, which is an increase of about 16% in the modelled estimate for Propel Holdings.
- Discount Rate has edged up slightly from 7.84% to 7.90%, reflecting a modestly higher required return in the valuation work.
- Revenue Growth has moved from 24.74% to 26.49%, indicating slightly stronger assumed top line expansion in the updated model.
- Net Profit Margin has eased from 13.68% to 13.07%, suggesting a small reduction in expected earnings retained from each dollar of revenue.
- Future P/E has increased from 6.54x to 7.32x, implying a somewhat higher valuation multiple applied to expected earnings for Propel Holdings.
Key Takeaways
- AI-powered risk assessment and digital adoption are boosting operational efficiencies, supporting strong credit performance and sustained revenue growth.
- Geographic expansion, product diversification, and scaling of Lending-as-a-Service are reducing risk exposure and driving more stable, diversified earnings.
- Intensifying competition, regulatory uncertainties, credit risk exposure, and rising operational costs threaten profitability and market position if growth initiatives fail to offset these pressures.
Catalysts
About Propel Holdings- Operates as a financial technology company.
- The ongoing tightening of traditional bank credit and increased rejection rates among mainstream lenders is pushing more high-quality consumers toward alternative credit sources like Propel, expanding their addressable market and directly supporting robust originations and revenue growth.
- Propel's continued investment and advancements in AI-powered risk assessment and automation are delivering both improved credit performance and increasing operational efficiencies, which are expected to drive future margin expansion and higher net income as the company scales.
- Acceleration of digital adoption, expanded smartphone usage, and persistent changes in employment patterns-such as growth in the gig economy-are sustaining and increasing demand for Propel's online and app-based credit products, likely supporting long-term top line growth.
- Expansion into new geographies (notably the U.K.) and diversified product offerings, along with a growing pipeline of business development initiatives and fintech partnerships, are set to widen revenue streams, reduce exposure to single-market risk, and smooth earnings volatility.
- Scaling of the Lending-as-a-Service business is expected to materially increase revenue and margin contribution, with the company signaling that this line will more than double into 2026, further supported by high partner satisfaction, strong capital availability, and improved operating leverage.
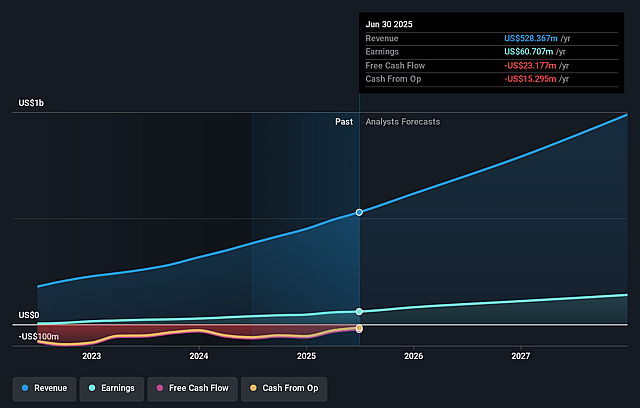
Propel Holdings Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Propel Holdings's revenue will grow by 26.5% annually over the next 3 years.
- Analysts assume that profit margins will increase from 8.8% today to 13.1% in 3 years time.
- Analysts expect earnings to reach $172.9 million (and earnings per share of $3.78) by about August 2029, up from $57.8 million today. However, there is a considerable amount of disagreement amongst the analysts with the most bullish expecting $194.1 million in earnings, and the most bearish expecting $151.0 million.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 7.4x on those 2029 earnings, down from 13.8x today. This future PE is lower than the current PE for the CA Consumer Finance industry at 11.5x.
- Analysts expect the number of shares outstanding to grow by 1.06% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 7.9%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Rising acquisition and data costs, especially as competition for lead generation and organic marketing intensifies, could continue to pressure net margins if customer acquisition costs increase faster than revenue growth.
- Regulatory risks remain elevated as Propel expands into new geographies; fragmented or tightening lending regulations, rate caps, or outright restrictions on high-interest loans could directly limit revenue potential and increase compliance and operating costs in key markets.
- Over-reliance on nonprime and subprime consumer segments, even as Propel seeks to move up the credit spectrum, leaves the company exposed to higher structural default risk and the possibility of worsening credit performance, which could negatively impact both net income and provisioning needs.
- Larger, well-capitalized financial institutions adopting advanced AI and open banking could leverage their scale and real-time data advantages to undercut Propel on pricing or credit terms, threatening Propel's market share and putting long-term pressure on revenues and operating leverage.
- Sustained operational investments (e.g., AI, new product launches, business development initiatives), while necessary for growth, could dampen net margin expansion if top-line growth slows or if these investments do not deliver commensurate improvements in productivity and profitability.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of CA$35.11 for Propel Holdings based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of CA$38.01, and the most bearish reporting a price target of just CA$28.81.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $1.3 billion, earnings will come to $172.9 million, and it would be trading on a PE ratio of 7.4x, assuming you use a discount rate of 7.9%.
- Given the current share price of CA$28.36, the analyst price target of CA$35.11 is 19.2% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Propel Holdings?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.