
Last Update 10 Jul 26
Fair value Decreased 28%GEN: Lower Growth Outlook And Dividend Will Shape Fair Future Returns
Genuit Group's latest analyst price target has been revised to reflect an updated fair value of £2.73, alongside refreshed assumptions on discount rate, revenue growth, profit margins and future P/E that analysts see as better aligning the stock with current expectations.
What's in the News for Genuit Group
- Genuit Group approved a final dividend of 8.7 pence per share for the year ended 31 December 2025, according to Key Developments data.
Valuation Changes for Genuit Group
- Fair Value has been reduced from £3.80 to £2.73, suggesting a lower central estimate for where analysts see the stock as fairly priced.
- The Discount Rate has been adjusted slightly higher from 9.23% to 9.97%, indicating a modestly higher required rate of return in the updated model.
- Revenue Growth has been revised from 7.69% to 4.07%, pointing to a more cautious outlook on future £ revenue expansion for Genuit Group.
- The Net Profit Margin has been trimmed slightly from 9.00% to 8.86%, reflecting a marginally lower expectation for future £ earnings per pound of sales.
- The Future P/E has been brought down from 18.67x to 15.70x, indicating that analysts are now using a lower earnings multiple in their valuation for Genuit Group.
Catalysts
About Genuit Group
Genuit Group provides climate, water and sustainable building solutions for the U.K. and selected international construction markets.
What are the underlying business or industry changes driving this perspective?
- Although AMP8 is set to materially expand the addressable market for plastic storm water and blue green roof solutions, any slippage in project approvals or slower than expected conversion from concrete to engineered plastic systems could delay the revenue uplift and push back the timing of margin recovery in Water Management, limiting near term operating profit growth.
- While tightening U.K. housing regulations around energy efficiency and the Future Home Standard should support higher value ventilation, underfloor heating and cooling packages, prolonged weakness in renovation and retrofit activity or extended transition periods could reduce the pace at which these higher ticket solutions translate into incremental revenue and earnings.
- Although demand for mechanical ventilation with heat recovery and integrated cooling is growing as overheating in homes becomes more common, execution risks in scaling manufacturing capacity, integrating recent acquisitions and managing wage inflation may cap the margin expansion that would otherwise flow from these higher specification product mixes.
- While the group’s focus on climate adaptation, recycled plastics and lean manufacturing should structurally improve cost efficiency, further delays in commercial construction approvals and potential cost overruns on modernization CapEx could offset productivity gains, constraining improvements in net margins and free cash flow.
- Although the balance sheet offers scope for bolt on deals in high growth niches such as underfloor heating and blue green roofs, overpaying for subscale targets or slower than planned post deal integration could dilute group returns and postpone the expected accretion to earnings and return on invested capital.
Assumptions
How have these above catalysts been quantified?
- This narrative explores a more pessimistic perspective on Genuit Group compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts.
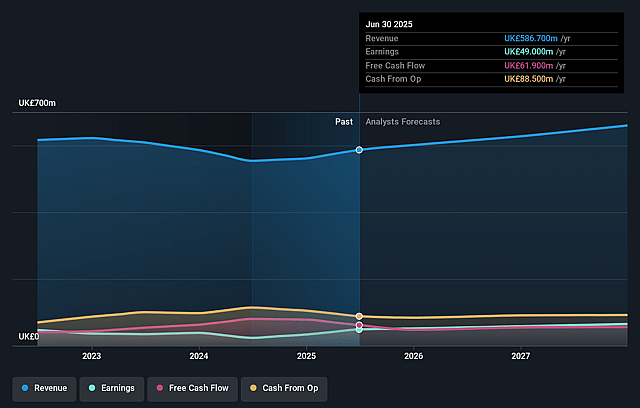
- The bearish analysts are assuming Genuit Group's revenue will grow by 4.1% annually over the next 3 years.
- The bearish analysts assume that profit margins will increase from 7.5% today to 8.9% in 3 years time.
- The bearish analysts expect earnings to reach £60.1 million (and earnings per share of £0.23) by about July 2029, up from £45.2 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as £77.8 million.
- In order for the above numbers to justify the price target of the more bearish analyst cohort, the company would need to trade at a PE ratio of 15.7x on those 2029 earnings, up from 14.1x today. This future PE is greater than the current PE for the GB Building industry at 13.9x.
- The bearish analysts expect the number of shares outstanding to grow by 1.19% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 9.97%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?
- Market volumes across U.K. construction are currently broadly flat, and management does not expect an increase in market volumes this year. If end markets stay muted for longer than anticipated or slip into decline, Genuit may struggle to sustain above-market growth, which would weigh on revenue and operating earnings over the medium term.
- The group is relying heavily on long-term U.K. regulatory tailwinds such as Future Home Standard, Awaab's Law and the AMP8 water cycle to drive higher-value solution sales. However, delays in implementation, extended transition periods or slower-than-expected project approvals could push out these benefits, limiting margin expansion and earnings growth.
- Wage inflation from National Insurance and Minimum Wage increases has already diluted EBIT margin despite revenue growth. If ongoing labour cost pressures outpace productivity gains from the Genuit Business System, net margins and overall profitability may fail to improve as guided.
- Strategic bolt-on acquisitions in underfloor heating and blue-green roofs are currently subscale and margin dilutive. If integration, scaling and cross-selling take longer than expected or end markets such as RMI underfloor heating remain weak, these deals could depress group margins and constrain earnings growth.
- Execution risk in Water Management, including slow-moving inventory issues, restructuring and the shift from product sales through merchants to larger direct project engagements, could mean the division does not reach the targeted 15 percent-plus margin, which would drag on group operating margin and free cash flow.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The assumed bearish price target for Genuit Group is £2.73, which represents up to two standard deviations below the consensus price target of £3.91. This valuation is based on what can be assumed as the expectations of Genuit Group's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of £5.0, and the most bearish reporting a price target of just £2.73.
- In order for you to agree with the more bearish analyst cohort, you'd need to believe that by 2029, revenues will be £678.7 million, earnings will come to £60.1 million, and it would be trading on a PE ratio of 15.7x, assuming you use a discount rate of 10.0%.
- Given the current share price of £2.53, the analyst price target of £2.73 is 7.4% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Genuit Group?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystLowTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystLowTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystLowTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Future Home Standard And Water Investment Will Drive Powerful Long Term Tailwinds
View narrative
New UK Regulations Will Expand Sustainable Building Markets
View narrative