
Last Update 03 Sep 26
Fair value Increased 7.83%2914: Combustible Share Execution And Dividend Policy Will Support Future Balanced Returns
Japan Tobacco’s analyst price target has been revised from ¥6,706.67 to ¥7,232.08, with analysts pointing to the company’s focus on combustible share and expectations for continued strong delivery as key drivers of the update.
What’s in the News for Japan Tobacco
- Japan Tobacco announced a second quarter cash dividend of ¥136.00 per share for the period ended June 30, 2026, compared with ¥104.00 per share for the same quarter a year earlier. The dividend is payable on September 1, 2026. Source: Company dividend announcement.
- For the full year ending December 31, 2026, Japan Tobacco expects to pay a total dividend of ¥136.00 per share, compared with ¥130.00 per share for the prior year. Source: Company dividend guidance.
- Japan Tobacco revised earnings guidance for the fiscal year ending December 31, 2026, with projected revenue of ¥3,885.0b, operating profit of ¥1,008.0b, profit attributable to owners of parents of ¥644.0b, and basic earnings per share of ¥362.74. Source: Company earnings guidance.
- The board of Japan Tobacco held a meeting on June 5, 2026, to consider disposal of treasury shares for restricted stock remuneration and performance share units, along with other business matters. Source: Company board meeting disclosure.
Valuation Changes for Japan Tobacco
- Fair value has risen from ¥6,706.67 to ¥7,232.08, which is an increase of about 7.8%.
- The discount rate is almost unchanged, moving slightly from 5.78% to 5.78% on a rounded basis.
- The revenue growth expectation is marginally lower, shifting from 5.37% to about 5.34%.
- The net profit margin has risen from 18.57% to about 19.76%, indicating a slightly higher assumed profitability for Japan Tobacco.
- The future P/E multiple has edged lower from 18.06x to about 17.68x, implying a slightly lower valuation multiple applied to expected earnings.
Key Takeaways
- Expansion into reduced-risk products and premium offerings drives sustained margin improvement, while innovation investment secures future earnings growth.
- International acquisitions and market share gains offset declines in mature markets, diversifying revenue and strengthening global competitive positioning.
- Heavy reliance on declining domestic markets, unprofitable reduced-risk products, and global regulatory, economic, and foreign exchange risks threaten profitability and revenue stability.
Catalysts
About Japan Tobacco- A tobacco company, manufactures and sells tobacco products, pharmaceuticals, and processed foods in Japan and internationally.
- Expansion of harm-reduction products like Ploom AURA and EVO addresses evolving consumer preferences for reduced-risk options, with segment share gains and plans for accelerated international rollout supporting sustained future revenue growth and improved net margins over the medium term.
- Strategic acquisitions (notably Vector Group in the U.S.) and continued international market share gains, especially in emerging markets with rising disposable incomes and expanding middle classes, position Japan Tobacco to offset volume declines in mature geographies and drive long-term revenue and operating profit diversification.
- Robust pricing power and portfolio premiumization, evidenced by successful launches at higher price points (e.g., premium EVO sticks) and effective price increases in markets like the Philippines, Italy, and the UK, underpin resilience in core revenue and the potential for sustainable net margin expansion.
- Ongoing R&D investment and a targeted ¥650 billion global allocation for innovation in next-generation products and marketing are likely to future-proof earnings and accelerate the path to profitability in the company's Reduced-Risk Product segment, positively impacting margins and long-term earnings growth.
- Industry-wide consolidation and shifting regulatory landscape create barriers to entry and enable further scale efficiencies for large incumbents like Japan Tobacco, bolstering competitive positioning and enabling improved operating leverage and bottom-line growth in less-regulated, high-potential regions.
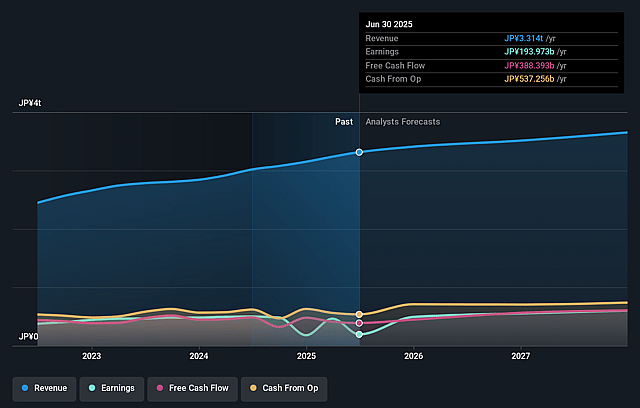
Japan Tobacco Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Japan Tobacco's revenue will grow by 5.3% annually over the next 3 years.
- Analysts assume that profit margins will increase from 16.4% today to 19.8% in 3 years time.
- Analysts expect earnings to reach ¥859.2 billion (and earnings per share of ¥484.01) by about September 2029, up from ¥610.0 billion today. However, there is a considerable amount of disagreement amongst the analysts with the most bullish expecting ¥1006.0 billion in earnings, and the most bearish expecting ¥710.9 billion.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 17.7x on those 2029 earnings, down from 20.4x today. This future PE is lower than the current PE for the JP Tobacco industry at 20.4x.
- Analysts expect the number of shares outstanding to remain consistent over the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 5.78%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- The company is heavily reliant on the Japanese domestic tobacco market, which continues to experience year-on-year declines in combustibles industry volume and overall market contraction, directly threatening a core source of revenue and profits.
- There is ongoing evidence of down-trading in key Asian and emerging markets, including Japan and the Philippines, where consumers shift to lower-priced products in response to price increases and weaker economic sentiment, eroding revenue growth and net margin expansion.
- While reduced-risk products (RRPs) and heated-tobacco (HTS) devices are showing growth, management indicates the RRP segment as a whole remains unprofitable, requiring massive investment (¥650 billion over three years) and is only targeting breakeven by 2028, meaning RRPs are a drag on overall group earnings until then.
- Foreign exchange volatility remains a persistent risk, as significant overseas earnings (especially from emerging markets) are subject to yen strength, with negative FX impacts already weighing on AOP and reported earnings, contributing potential downside to net margins and profit growth.
- The industry continues to face global regulatory tightening, litigation costs (e.g., Canadian settlements), tax hikes, and possible new tariffs, all of which can compress profit margins, increase operating costs, and reduce legitimate demand-negatively impacting top-line revenue and overall profitability.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of ¥7232.08 for Japan Tobacco based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of ¥8400.0, and the most bearish reporting a price target of just ¥6100.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be ¥4347.3 billion, earnings will come to ¥859.2 billion, and it would be trading on a PE ratio of 17.7x, assuming you use a discount rate of 5.8%.
- Given the current share price of ¥7003.0, the analyst price target of ¥7232.08 is 3.2% higher. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Japan Tobacco?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Global Regulation And Combustible Decline Will Erode Tobacco Earnings Power Over Time
View narrative
Heated Tobacco Expansion And RRP Investment Will Transform Long Term Earnings Quality
View narrative