
Last Update 17 Sep 26
Fair value Increased 5.34%ANDR: Fair Value View Will Hinge On Execution Into 2026
Analysts have lifted their fair value estimate for Andritz from €87.33 to €92.00, reflecting updated assumptions on discount rate, revenue growth, profit margins and future P/E that align with recent increases in Street price targets to €93.
Analyst Commentary
Recent price target moves on Andritz give you a sense of how bullish analysts are thinking about valuation, execution and growth potential right now. The fair value range discussed by the Street has shifted into the low €90s, which is close to the latest price target of €93 from JPMorgan.
Bullish Takeaways
- Bullish analysts see the move from €77 to €87 and now to €93 as support for a higher valuation range for Andritz, which aligns with the recent fair value lift to €92.00.
- The repeated use of an Overweight rating suggests confidence in Andritz executing on its business plan well enough to justify a premium P/E versus where it traded when targets were closer to €77.
- The clustering of targets around €92 to €93 is viewed as a sign that Street models are converging, which can reduce uncertainty around what analysts consider a reasonable valuation anchor.
- The cadence of upward target revisions over multiple research updates is interpreted by bullish analysts as a sign that Andritz has been tracking broadly in line with or better than earlier expectations embedded in their models.
Bearish Takeaways
- The latest €93 price target still implies limited headroom above the €92.00 internal fair value estimate, which may leave less margin of safety for investors who want a wider discount to analysts’ targets.
- Repeated Overweight ratings can encourage investors to price in strong execution from Andritz, which raises the risk that any operational setbacks or weaker order trends could weigh more heavily on the stock.
- The tight cluster of targets in a narrow band may signal that many assumptions around growth, margins and future P/E are already fully reflected, leaving less scope for upside surprise if conditions only match current forecasts.
- With targets already reset higher, bearish analysts may argue that the balance of risk and reward is less compelling than when Andritz was being valued on earlier targets closer to €77.
What’s in the News for Andritz
- Andritz AG received a contract from Vodohospodárska Výstavba to modernize the Gabcíkovo hydroelectric power plant on the Danube in Slovakia, a facility that accounts for about 10% of the country’s electricity production, with the order value described as in the mid three digit million euro range. Source: Client announcement.
- The Gabcíkovo project covers a full renewal of electromechanical equipment for the 720 MW plant. This includes refurbishment of eight Kaplan turbine generator units, upgrades to automation, protection and control systems, and renewal of transformers and auxiliary electrical systems. The work is scheduled to be included in Andritz AG’s order intake for the third quarter of 2026. Source: Client announcement.
- As part of the Gabcíkovo modernization, the objective is to improve efficiency and availability and to extend the technical service life of key operating equipment by at least 30 years. The work will be carried out sequentially to keep the plant available during the project. Source: Client announcement.
- Andritz AG confirmed earnings guidance for 2026, with revenue guided to a range of €8b to €8.3b. Source: Corporate guidance update.
- UPM and Andritz signed a multi year cooperation agreement focused on tissue manufacturing, giving tissue producers access to Andritz’s PrimeLineTIAC Tissue Innovation and Application Center in Graz and using UPM hardwood pulp UPM Euca as the standard pulp for all customer and internal trials. Source: Key developments.
Valuation Changes for Andritz
This section gives you a quick view of how key valuation inputs for Andritz have shifted in the latest update. It helps you see which levers in the model now carry more weight and which ones have been dialed back.
- Fair Value increased from €87.33 to €92.00, which is a rise of about 5.3% in the central valuation estimate.
- Discount Rate risen slightly from 7.31% to about 7.46%, indicating a modestly higher required return in the model.
- Revenue Growth moved from about 6.27% to around 7.00%, pointing to a slightly higher assumed € revenue trajectory.
- Net Profit Margin edged down from roughly 7.11% to about 7.01%, which reflects a small reduction in expected profitability on each € of sales.
- Future P/E increased from about 15.64x to roughly 16.46x, signalling a somewhat higher valuation multiple applied to Andritz earnings in the updated framework.
Key Takeaways
- Strong order intake, record backlog, and favorable market trends position Andritz for revenue and margin growth, especially in hydropower and through expansion in services.
- Portfolio diversification via acquisitions and a higher share of recurring service revenue will boost resilience and support sustainable long-term profitability.
- Overdependence on cyclical markets, operational inefficiencies, and challenging market and currency conditions heighten risks to revenue stability, margin recovery, and long-term earnings sustainability.
Catalysts
About Andritz- Engages in the provision of industrial machinery, equipment, and services in Europe, North America, South America, China, Asia, Africa, Australia, and internationally.
- The surge in order intake (+26% in Q2, +23% YTD) across Hydropower, Metals, and a recovering Pulp & Paper segment, combined with a record-high order backlog (€10.4bn), positions Andritz for a significant revenue rebound as backlogged projects are executed and as macro trends (decarbonization, infrastructure renewal) continue to spur end-market demand.
- Hydropower, benefiting from the global transition toward renewable energy and electrification, is at the start of a structural upcycle with multi-year growth visibility, increasing order volumes and service revenues-implying sustained top-line and eventual margin growth from higher project activity and recurring services.
- Aftermarket and service share of revenue reached a new high (44%), with recent M&A deals specifically targeting complementary service and digital assets; this shift is expected to drive recurring revenue, improve net margins, and increase resilience to cyclical downturns.
- Recent capacity reductions and restructuring in Pulp & Paper and Metals are nearly complete, which should lower the cost base and set the stage for margin recovery in these divisions as revenue normalizes, potentially unlocking operating leverage and boosting earnings.
- Ongoing strategic acquisitions in niche technologies (e.g., automation, sustainability, and regional fill-ins in paper, metals, and energy) accelerate portfolio diversification and digital capabilities, positioning Andritz to capture growth from automation and decarbonization trends and supporting both revenue growth and margin expansion long term.
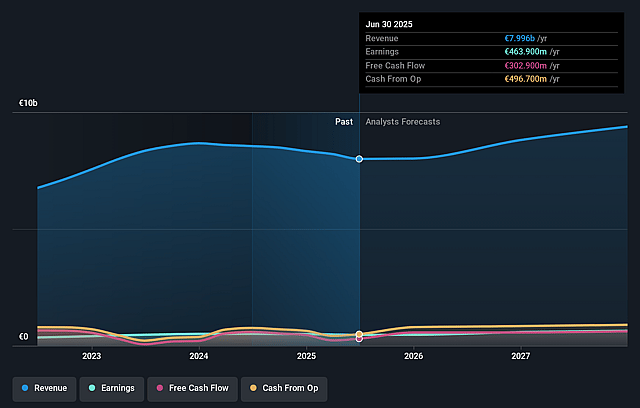
Andritz Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Andritz's revenue will grow by 7.0% annually over the next 3 years.
- Analysts assume that profit margins will increase from 5.8% today to 7.0% in 3 years time.
- Analysts expect earnings to reach €693.3 million (and earnings per share of €7.03) by about September 2029, up from €465.5 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as €816.7 million.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 16.5x on those 2029 earnings, down from 17.6x today. This future PE is greater than the current PE for the GB Machinery industry at 12.1x.
- Analysts expect the number of shares outstanding to grow by 0.67% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 7.46%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Continued revenue decline in the Pulp & Paper and Metals business areas, driven by last year's low order intake, highlights overreliance on cyclical end-markets-raising the risk of earnings volatility and sustained pressure on overall revenue if demand fails to rebound as expected.
- Weakness and uncertainty in the Environment & Energy segment, with customers delaying investment decisions and muted activity in Pumps and Separation, signal exposure to market hesitancy and slow adoption of new sustainable solutions, potentially impacting long-term growth and earnings quality.
- The need for ongoing capacity reductions and restructuring in Pulp & Paper and Metals indicates possible operational inefficiencies and delayed margin recovery; restructuring charges have already reduced reported margins and net income, and execution risk remains if demand does not improve swiftly.
- Margin and revenue headwinds from unfavorable FX trends, especially the strengthening euro, are expected to persist, directly reducing reported top-line and potentially compressing net margins if the currency environment does not stabilize.
- Increasing capital allocation to M&A, combined with decreasing net liquidity and a rising proportion of smaller, lower-margin orders, exposes Andritz to balance sheet strain and integration risk, with the possibility that new acquisitions may not deliver anticipated margin uplift or long-term earnings growth.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of €92.0 for Andritz based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of €100.0, and the most bearish reporting a price target of just €80.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be €9.9 billion, earnings will come to €693.3 million, and it would be trading on a PE ratio of 16.5x, assuming you use a discount rate of 7.5%.
- Given the current share price of €83.5, the analyst price target of €92.0 is 9.2% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Andritz?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Decarbonization And Digitalization Will Power Sustainable Industrial Progress
View narrative
Legacy Hydropower And Pulp Challenges Will Weaken Future Prospects
View narrative