
Last Update 25 Aug 26
Fair value Decreased 5.54%EEFT: Future Returns Will Weigh Macro Pressures Against Execution And Buyback Support
Analysts have nudged their blended price target for Euronet Worldwide lower from $75 to about $70.85, reflecting trimmed forecasts after slightly softer Q2 results and ongoing macro and immigration related pressures, even as sector research still cites healthy U.S. consumer and credit trends.
Analyst Commentary
Recent analyst commentary on Euronet Worldwide points to a more cautious stance, with several firms trimming price targets after Q2 results that came in below some expectations. Readers looking at the stock today are seeing a mix of concern about execution against forecasts and the impact of external pressures such as macro trends and immigration related headwinds.
Bearish analysts highlight that Q2 total revenue and EPS were below certain prior forecasts, which raises questions about how confidently Euronet Worldwide can hit earlier earnings trajectories. Even though sector research still points to healthy U.S. consumer and credit trends, these supportive data points have not prevented more conservative assumptions for the company.
Bearish Takeaways
- Bearish analysts have cut price targets, with one moving from US$75 to US$70 and another from US$102 to US$94, which reflects reduced confidence in near term upside for Euronet Worldwide.
- Q2 total revenue came in 1% below at least one forecast and EPS missed that forecast by 4%, which adds to concerns about execution risk and the reliability of previous growth assumptions.
- There is ongoing concern about macroeconomic pressures and U.S. efforts to control immigration, which bearish analysts see as potential constraints on transaction volumes and growth opportunities for Euronet Worldwide.
- The combination of forecast trims and lower price targets suggests that some on the Street are more cautious on valuation and are building in higher risk around earnings delivery for the company.
What’s in the News for Euronet Worldwide
- Euronet Worldwide updated its share buyback activity for the period from April 1, 2026 to June 30, 2026, reporting the repurchase of 706,299 shares for US$50 million, representing 1.86% of the company. Source, Key Developments.
- The company reported that, under the buyback program announced on February 23, 2022, it has now completed the repurchase of 17,799,002 shares for US$1,631.83 million, which represents 40.47% of the company. Source, Key Developments.
- These buyback figures give readers a current snapshot of how Euronet Worldwide has been using capital for share repurchases through the end of Q2 2026. Source, Key Developments.
Valuation Changes for Euronet Worldwide
- Fair value was reduced from $75.00 to $70.85, which is a modest cut of around 6% in the valuation estimate for Euronet Worldwide.
- The discount rate moved higher from 8.73% to 9.12%, which signals a slightly higher required return being applied to the stock.
- Revenue growth was adjusted from 5.65% to 3.20%, which is a meaningful step down in projected top line expansion using dollar-based projections.
- The net profit margin was revised from 8.64% to 6.73%, which points to lower assumed earnings efficiency on future dollar revenue.
- The future P/E increased from 6.54x to 8.53x, which indicates a higher earnings multiple being used in the updated valuation framework.
Catalysts
About Euronet Worldwide
Euronet Worldwide operates a global payments, money transfer and digital asset infrastructure network serving banks, merchants, brands and consumers.
What are the underlying business or industry changes driving this perspective?
- Although the Ren platform and pending CoreCard acquisition position Euronet to benefit from the multi-year shift toward real-time, cloud-based issuing and acquiring, long implementation cycles and potential delays in customer ramp could defer expected processing volumes and slow operating margin expansion.
- While partnerships such as Citi, Commonwealth Bank of Australia and Union Bank align Euronet with the continued globalization of cross-border, real-time payments, regulatory scrutiny on cross-border flows and evolving compliance requirements may cap throughput growth and weigh on Money Transfer segment earnings.
- Although rising digital adoption in epay and Money Transfer supports higher-margin, asset-light revenue streams over time, consumer discretionary pressures in gaming and online content and slower digital take-up in key migrant populations could limit top line acceleration and delay net margin improvement.
- While stablecoin on- and off-ramp capabilities and the GENIUS Act framework give Euronet an early infrastructure edge in regulated digital assets, slower institutional adoption or technology and cybersecurity setbacks could restrict new use cases and temper incremental revenue contributions.
- Although global ATM network expansion in emerging markets and outsourcing deals in cash desert regions support fee and FX income, prolonged economic weakness and structurally lower vacation spending in Europe may force a sharper cull of marginal locations, constraining revenue growth and pressuring segment-level earnings.
Assumptions
How have these above catalysts been quantified?
- This narrative explores a more pessimistic perspective on Euronet Worldwide compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts.
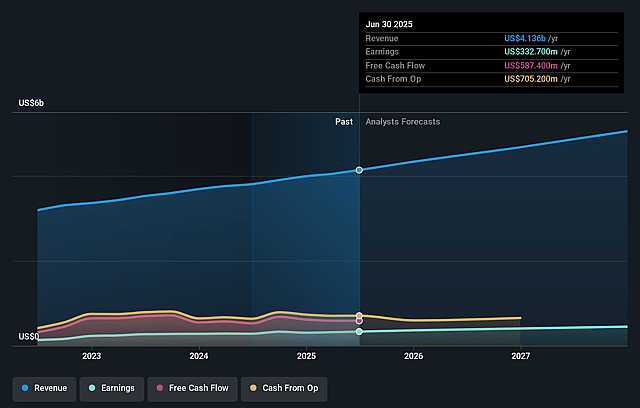
- The bearish analysts are assuming Euronet Worldwide's revenue will grow by 3.2% annually over the next 3 years.
- The bearish analysts assume that profit margins will increase from 6.6% today to 6.7% in 3 years time.
- The bearish analysts expect earnings to reach $323.6 million (and earnings per share of $7.23) by about August 2029, up from $288.4 million today. The analysts are largely in agreement about this estimate.
- In order for the above numbers to justify the price target of the more bearish analyst cohort, the company would need to trade at a PE ratio of 8.6x on those 2029 earnings, down from 9.2x today. This future PE is lower than the current PE for the US Diversified Financial industry at 17.8x.
- The bearish analysts expect the number of shares outstanding to decline by 7.0% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 9.12%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?
- Persistent global economic weakness and elevated inflation could further squeeze consumer discretionary spending on travel, gaming and digital content, slowing transaction growth in EFT and epay and limiting revenue expansion and operating margin improvement over the long term.
- Prolonged tightening or renewed waves of restrictive immigration and remittance policies in the U.S. and other developed markets could structurally depress money transfer volumes on key corridors, undermining the long term growth trajectory of cross-border revenues and segment earnings.
- If digital remittance and payments adoption plateaus below management expectations due to enduring customer preference for cash and over the counter services, the mix shift toward higher margin digital channels may stall and constrain improvements in consolidated net margins and earnings growth.
- Execution and adoption risks around stablecoin and tokenized payment use cases, including regulatory setbacks, cybersecurity issues or slower institutional uptake, could delay or reduce the anticipated efficiency gains and high margin revenue streams that underpin longer term earnings accretion.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The assumed bearish price target for Euronet Worldwide is $70.85, which represents up to two standard deviations below the consensus price target of $86.67. This valuation is based on what can be assumed as the expectations of Euronet Worldwide's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $94.0, and the most bearish reporting a price target of just $70.0.
- In order for you to agree with the more bearish analyst cohort, you'd need to believe that by 2029, revenues will be $4.8 billion, earnings will come to $323.6 million, and it would be trading on a PE ratio of 8.6x, assuming you use a discount rate of 9.1%.
- Given the current share price of $71.21, the analyst price target of $70.85 is 0.5% lower. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Euronet Worldwide?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystLowTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystLowTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystLowTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Digital Payments And Remittances Will Drive Long Term Upside Potential
View narrative
EEFT: Resilient Consumer Spending Will Support Positive Momentum Amid Uncertainty
View narrative