
Last Update 03 Sep 26
Fair value Increased 3.48%OVV: Inventory Additions And Weaker Margins Will Likely Limit Future Returns
Analysts have lifted their price target for Ovintiv from $58.41 to $60.44. This reflects updated assumptions around fair value, a slightly weaker revenue outlook, lower profit margin expectations, and a higher future P/E multiple.
What’s in the News for Ovintiv
- Ovintiv updated its 2026 ground game acquisition program with over 60 transactions that add approximately 41,000 net acres across its Montney and Permian assets, along with 240 net well locations acquired at what the company describes as attractive valuations. Source Ovintiv Announces Permian and Montney Inventory Additions.
- The acquisition program carries an estimated total cost of about US$460 million, or roughly US$11,000 per net acre and about US$1.3 million to US$1.7 million per well location after adjusting for minimal production from the acquired assets. Source company update on 2026 ground game acquisition program.
- In the Permian, Ovintiv is adding around 21,000 net acres and 120 total well locations in the Midland basin for about US$230 million, while in the Montney it is adding about 20,000 net acres and 120 well locations in the liquids rich Alberta oil window for a similar amount. Source company update on 2026 ground game acquisition program.
- Ovintiv reported second quarter 2026 production of 614.6 MBOE/d, with oil and plant condensate production of 205.8 Mbbls/d, total liquids production of 288.2 Mbbls/d, and natural gas production of 1,959 MMcf/d. Source Announcement of Operating Results.
- From 1 April 2026 to 30 June 2026, Ovintiv repurchased 6,105,772 shares for US$344.85 million, completing the repurchase of 7,593,028 shares for US$428.87 million under its existing buyback program. Source Buyback Tranche Update.
Valuation Changes for Ovintiv
- Fair Value moved from $58.41 to $60.44, which is a modest upward revision to the estimated share valuation.
- Discount Rate is unchanged at 7.24%, indicating no adjustment to the required rate of return used in the valuation model.
- Revenue Growth expectations show a slightly steeper decline, shifting from a 6.26% fall to a 6.61% fall.
- Net Profit Margin expectations have fallen from 19.42% to 16.14%, pointing to a lower projected level of earnings relative to revenue for Ovintiv.
- Future P/E has risen from 15.93x to 20.07x, indicating that the updated valuation assumes a higher earnings multiple for the stock.
Key Takeaways
- Infrastructure bottlenecks, regulatory risks, and energy transition pressures create persistent headwinds for long-term growth and profitability in core plays.
- Sustained earnings require ongoing capital reinvestment and overcoming diminishing returns from efficiency gains in increasingly mature shale assets.
- Structural industry headwinds, regulatory pressures, and capital market challenges threaten Ovintiv’s margins, cash flow stability, and long-term growth due to the global shift from fossil fuels.
Catalysts
About Ovintiv- Explores, develops, produces, and markets natural gas, oil, and natural gas liquids in North America.
- While Ovintiv stands to benefit from the anticipated growth in global energy demand and the build-out of North American LNG export capacity, persistent infrastructure bottlenecks in key basins like Western Canada and exposure to localized gas price markers may limit Ovintiv’s realized prices and constrain top-line revenue growth if not proactively addressed with further diversification.
- Although Ovintiv’s portfolio optimization has resulted in significant exposure to low-cost shale plays and high productivity assets in the Permian, Montney, and Anadarko, these regions face growing regulatory risk, increasing environmental scrutiny, and uncertain regulatory reform both in the US and Canada, which could drive up long-term compliance and operating costs and erode net margins.
- The company’s discipline in capital allocation and focus on free cash flow yield support share buybacks and debt reduction, yet continual reinvestment is needed to replenish relatively short reserve life and sustain flat production, creating potential long-term headwinds for earnings stability if commodity prices weaken or operational outperformance stalls.
- Although technological innovation in drilling and completion has driven industry-leading capital efficiency and lower costs per barrel, efficiency improvements may become incrementally harder to achieve as the shale maturity advances, risking plateauing operational gains and thereby limiting further margin expansion in future years.
- While rising global energy demand and new LNG demand channels should support overall revenue potential, the accelerating energy transition and global policy shifts toward decarbonization may cap long-term demand for Ovintiv’s oil and gas assets, presenting structural revenue and margin challenges as renewable energy alternatives become increasingly competitive.
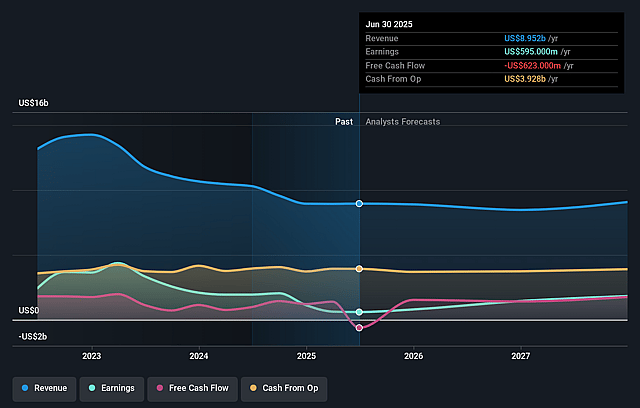
Ovintiv Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- This narrative explores a more pessimistic perspective on Ovintiv compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts.
- The bearish analysts are assuming Ovintiv's revenue will decrease by 6.6% annually over the next 3 years.
- The bearish analysts assume that profit margins will increase from 9.7% today to 16.1% in 3 years time.
- The bearish analysts expect earnings to reach $1.3 billion (and earnings per share of $5.28) by about September 2029, up from $920.0 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as $2.5 billion.
- In order for the above numbers to justify the price target of the more bearish analyst cohort, the company would need to trade at a PE ratio of 20.1x on those 2029 earnings, up from 20.0x today. This future PE is greater than the current PE for the US Oil and Gas industry at 12.9x.
- The bearish analysts expect the number of shares outstanding to grow by 7.0% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 7.24%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Long-term global energy transition away from fossil fuels could gradually erode oil and natural gas demand, creating structural headwinds for Ovintiv’s core revenue and threatening the stability of its cash flow as renewables capture a greater share of the market.
- Heightened regulatory pressure and carbon pricing, especially in Canada and the United States, may significantly increase Ovintiv's ongoing compliance and operating costs, which would compress net margins over time as governments intensify their focus on emissions reduction.
- Rising investor demand and public scrutiny for strong ESG (Environmental, Social, and Governance) performance could make it harder or more expensive for Ovintiv to access debt and equity capital, which risks raising its cost of capital and limiting future investment flexibility needed to sustain earnings growth.
- Ovintiv’s shale-focused portfolio requires substantial and recurring capital expenditure for continuous drilling to offset its comparatively short reserve life, and any unexpected commodity price downturn could undermine free cash flow and ultimately pressure net margins and earnings consistency if capital markets tighten.
- Volatile commodity pricing cycles, exacerbated by factors like global oversupply, policy changes from OPEC+ or geopolitical instability, create persistent uncertainty for Ovintiv's realized prices and revenue, increasing earnings volatility and potentially deterring long-term investor confidence.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The assumed bearish price target for Ovintiv is $60.44, which represents up to two standard deviations below the consensus price target of $74.43. This valuation is based on what can be assumed as the expectations of Ovintiv's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $85.0, and the most bearish reporting a price target of just $55.0.
- In order for you to agree with the more bearish analyst cohort, you'd need to believe that by 2029, revenues will be $7.8 billion, earnings will come to $1.3 billion, and it would be trading on a PE ratio of 20.1x, assuming you use a discount rate of 7.2%.
- Given the current share price of $66.91, the analyst price target of $60.44 is 10.7% lower. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Ovintiv?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystLowTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystLowTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystLowTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Share Repurchase Plan Will Drive Future Gains Despite Margin Pressure
View narrative
North American Shale Will Benefit From Rising Global Energy Demand
View narrative