
Last Update 17 Sep 26
Fair value Increased 5.39%DRH: Higher Lodging Demand And Cautious Outlook Will Shape Future P/E
Analysts have nudged their fair value estimate for DiamondRock Hospitality higher from $11.00 to about $11.59, citing updated models that reflect recent price target increases across the Street and steady demand trends in urban and resort lodging markets.
Analyst Commentary
Recent Street research on DiamondRock Hospitality points to a cluster of higher price targets across a range of firms. Analysts highlight steady lodging demand in urban and resort markets, along with ongoing interest in higher average daily rate assets and exposure to higher spending travelers. Even with these constructive elements, the tone is not uniformly bullish, and several research notes flag areas where execution and growth could be tested.
Updates following Q2 earnings across the lodging and leisure group reference stronger revenue trends and some upward estimate revisions. At the same time, commentary points to the need for management teams to provide more confident guidance beyond a single quarter and to address how current conditions might influence results through 2026 and 2027. For DiamondRock Hospitality, this mix of higher targets and cautious messaging leaves investors weighing valuation support against potential growth and execution risks.
Some research also frames DiamondRock within a broader view of lodging real estate investment trusts, where expectations around group demand, high-end consumer resilience, and revenue per available room trends set the backdrop. As of September 2026, investors are working with a Street view that is constructive but not unanimous, which can be useful context when thinking about position sizing and risk tolerance.
Bearish Takeaways
- Bearish analysts describe second half outlooks across lodging as tempered, which can limit enthusiasm for DiamondRock Hospitality if investors are looking for clear acceleration in revenue or earnings growth.
- Comments that recent share performance has already captured Q2 revenue per available room strength suggest some concern that the stock could be pricing in a lot of good news, raising the risk of disappointment if execution falters.
- References to Equal Weight or Neutral stances signal that some bearish analysts see a balance between upside and downside, which can indicate uncertainty about DiamondRock’s ability to outperform peers on growth or capital allocation.
- Notes that investors want more confident tones from management teams beyond short term beats underscore a view that DiamondRock still needs to prove durability of demand and growth before supporting materially higher valuation multiples.
What’s in the News for DiamondRock Hospitality
- DiamondRock Hospitality is actively reviewing potential hotel acquisitions after its Second Quarter 2026 earnings call, with management describing the transaction market as healthier and highlighting a focus on free cash flow per share and internally funded growth. Source: Company earnings call commentary.
- The company plans to stay active on both acquisitions and property sales over the next 6 to 12 months, with management emphasizing goals to support earnings growth, manage risk and pursue opportunities where they see a path to higher cash flow and long term value. Source: Company earnings call commentary.
- From April 28, 2026 to July 30, 2026, DiamondRock Hospitality repurchased 52,901 shares for US$0.58 million, which represents 0.03% of its shares under the buyback announced on April 30, 2026. Source: Buyback tranche update.
- On July 30, 2026, the Board declared a third quarter 2026 cash dividend of US$0.11 per share, which is 22% higher than the second quarter dividend. The company also stated an expectation of regular quarterly dividends of US$0.11 per share for the remainder of 2026 and a possible stub dividend in the fourth quarter, subject to 2026 operating income. Source: Dividend announcement.
- DiamondRock Hospitality was dropped from the Russell 2000 Dynamic Index earlier in 2026, which may influence how some index funds and benchmarks are exposed to the stock. Source: Index constituent change.
Valuation Changes for DiamondRock Hospitality
- Fair Value has risen slightly from $11.00 to about $11.59, which is an increase of roughly 5% in the updated assessment.
- Discount Rate has edged lower from 8.31% to about 8.24%, which points to a modest reduction of roughly 0.07 percentage points in the required return used in the model.
- Revenue Growth has moved from 1.98% to about 2.09%, a small upward shift of roughly 0.11 percentage points in projected revenue expansion.
- Net Profit Margin has increased from 10.46% to about 11.84%, which is a change of roughly 1.38 percentage points in expected earnings efficiency.
- Future P/E has been marked down from 22.95x to about 21.25x, a reduction of roughly 7%, which implies a slightly lower valuation multiple on expected earnings for DiamondRock Hospitality.
Key Takeaways
- Reliance on leisure and resort markets heightens vulnerability to economic shocks, discretionary spending slowdowns, and competitive threats from short-term rental platforms.
- Rising labor costs, renovation needs, and supply chain risks pressure operating margins and limit financial flexibility for investments or dividends.
- Strategic reinvestment in high-barrier urban properties, supported by strong demand and disciplined capital allocation, positions the company for sustained profitability and long-term shareholder value.
Catalysts
About DiamondRock Hospitality- A self-advised real estate investment trust (REIT) that is an owner of a leading portfolio of geographically diversified hotels concentrated in leisure destinations and top gateway markets.
- The acceleration of remote and hybrid work models continues to weaken business travel growth, creating persistent risk to DiamondRock’s future occupancy rates and revenue, particularly as first-quarter business transient demand improvement is unlikely to offset this long-term structural decline.
- DiamondRock's substantial exposure to leisure-oriented and drive-to resort markets heightens vulnerability to downturns in discretionary spending and deepens exposure to economic shocks, threatening both revenue and EBITDA margin stability as macroeconomic anxiety persists and disposable incomes stagnate for the middle class.
- The company faces ongoing labor scarcity and rising wage pressures, with wage and benefit growth already tracking at three to three and a half percent for the year ahead, pressuring operating costs and compressing net margins even as DiamondRock’s ability to find additional cost reductions diminishes post-pandemic.
- Competition from short-term rental platforms like Airbnb and VRBO continues to draw away both leisure and group demand, leading to increased pricing pressure, lower average daily rates, and eroding RevPAR growth for hotel REITs such as DiamondRock, directly impacting revenue and profitability.
- The ongoing necessity to renovate and reposition aging properties, compounded by supply chain risks and potential tariff hikes on imported furnishings, threatens to inflate capital expenditures and asset maintenance costs, thereby constraining free cash flow available for dividends or reinvestment and increasing risk of future asset write-downs.
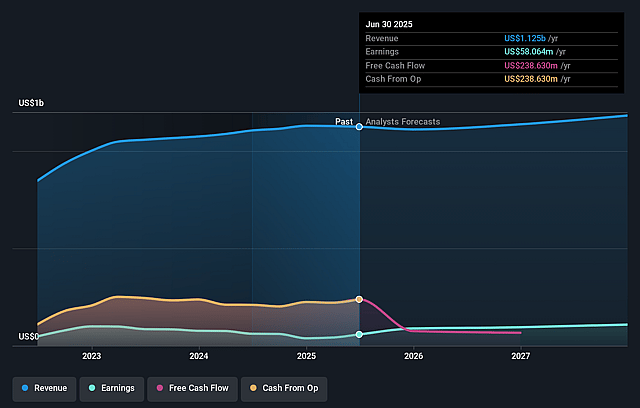
DiamondRock Hospitality Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- This narrative explores a more pessimistic perspective on DiamondRock Hospitality compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts.
- The bearish analysts are assuming DiamondRock Hospitality's revenue will grow by 2.1% annually over the next 3 years.
- The bearish analysts assume that profit margins will shrink from 13.1% today to 11.8% in 3 years time.
- The bearish analysts expect earnings to reach $143.2 million (and earnings per share of $0.73) by about September 2029, down from $148.8 million today. The analysts are largely in agreement about this estimate.
- In order for the above numbers to justify the price target of the more bearish analyst cohort, the company would need to trade at a PE ratio of 21.3x on those 2029 earnings, up from 16.9x today. This future PE is lower than the current PE for the US Hotel and Resort REITs industry at 25.5x.
- The bearish analysts expect the number of shares outstanding to grow by 0.44% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 8.24%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Sustained RevPAR growth in the urban portfolio, highlighted by a 5% year-over-year increase and steady improvements in group and transient business demand, suggests underlying revenue momentum that could buoy long-term revenues and profitability.
- Successful property renovations and repositioning, as seen with the Westin San Diego Bayview and Bourbon Orleans, are generating substantial post-renovation lifts in RevPAR and net operating income, indicating that capital reinvestment may continue to drive earnings and margin expansion.
- The company’s focus on high-barrier-to-entry urban and resort markets with minimal competitive supply growth provides long-term protection against oversupply, supporting room rates, occupancy, and net cash flow stability in future periods.
- Active and accretive share repurchases, along with disciplined capital recycling and a flexible balance sheet, enhance per-share earnings and return on equity, which could underpin share price appreciation and investor returns.
- Resilient leisure and group demand, supported by broader secular travel trends and a diversified portfolio strategy, positions DiamondRock to benefit from ongoing growth in domestic travel and consumer experience spending, aiding sustained revenue and adjusted EBITDA growth over time.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The assumed bearish price target for DiamondRock Hospitality is $11.59, which represents up to two standard deviations below the consensus price target of $13.96. This valuation is based on what can be assumed as the expectations of DiamondRock Hospitality's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $16.0, and the most bearish reporting a price target of just $11.0.
- In order for you to agree with the more bearish analyst cohort, you'd need to believe that by 2029, revenues will be $1.2 billion, earnings will come to $143.2 million, and it would be trading on a PE ratio of 21.3x, assuming you use a discount rate of 8.2%.
- Given the current share price of $12.27, the analyst price target of $11.59 is 5.8% lower. The relatively low difference between the current share price and the analyst consensus price target indicates that they believe on average, the company is fairly priced.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on DiamondRock Hospitality?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystLowTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystLowTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystLowTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Read more narratives

Urban And Bleisure Travel Trends Will Unlock Future Value
View narrative
Experiential Hotels Will Benefit From Rising Premium Leisure Travel
View narrative