

Last Update 07 Aug 26
Fair value Increased 2.23%J: Infrastructure And AI Contracts Will Drive Backlog-Fueled Upside Potential
Analysts have nudged their price target for Jacobs Solutions higher to $161.80 from $158.27. This reflects updated views on fair value, discount rate assumptions, profit margins and future P/E expectations.
What’s in the News for Jacobs Solutions
- Jacobs Solutions raised its fiscal 2026 profit forecast ahead of Q3 2026 earnings, supported by a backlog of about $27b and recent critical infrastructure and AI data center contract wins. Source: Recent earnings preview coverage.
- The company was selected by LA Metro, working with Clark Construction Group, to design and build advanced charging infrastructure at two major bus divisions as LA moves to a zero emission bus fleet before the 2028 Olympic and Paralympic Games. Source: LA Metro client announcement.
- Jacobs secured a seven year multidisciplinary framework with Germany’s TransnetBW to support grid expansion and renewable integration, covering project controls, engineering, environmental services and construction oversight. Source: TransnetBW framework announcement.
- RBC Capital reaffirmed its Buy rating on Jacobs Solutions with a price target of $171, while the average analyst rating remains Moderate Buy with a consensus target of $159.75. Recent insider buying includes a purchase by Chair and CEO Robert Pragada. Source: Globe and Mail analyst coverage.
- The company won a sole source EPCM contract from Hut 8 for a second US AI data center campus in Texas that is designed for up to one gigawatt of capacity, using a digital twin approach to help manage design and commissioning risk. Source: Hut 8 project announcement.
Valuation Changes for Jacobs Solutions
- Fair Value has risen slightly, moving from $158.27 to $161.80 per share.
- Discount Rate has edged lower, shifting from 7.94% to about 7.84%.
- Revenue Growth expectation has been trimmed, moving from about 7.40% to about 6.99%.
- Net Profit Margin forecast is slightly higher, shifting from about 6.58% to about 6.63%.
- Future P/E assumption has fallen, moving from about 20.93x to about 19.14x.
Key Takeaways
- Strong momentum in digital transformation and infrastructure modernization drives sustainable revenue and margin growth across high-priority markets.
- Strategic focus on consulting, technology, and disciplined capital returns bolsters higher-quality earnings and increasing shareholder value.
- Reliance on public sector spending, capital-intensive growth initiatives, and project execution risks expose Jacobs to revenue volatility, margin pressure, and potential earnings underperformance.
Catalysts
About Jacobs Solutions- Engages in the infrastructure and advanced facilities, and consulting businesses in the United States, Europe, Canada, India, Asia, Australia, New Zealand, the Middle East, and Africa.
- Record-high backlog growth (up 14% year-over-year) in Water, Advanced Facilities, and Critical Infrastructure-driven by global infrastructure modernization, water scarcity, and data center expansion-provides strong visibility into multi-year revenue growth and supports confidence in accelerating top-line results into FY '26 and beyond.
- Rapid adoption of digital transformation-exemplified by growing Digital Twin engagements, the transformational NVIDIA Omniverse partnership, and expanding AI/data center projects-positions Jacobs to capture high-margin, recurring digital services revenue, further supporting sustainable net margin and EPS growth.
- Rising public and private sector investments in climate adaptation, water modernization, and decarbonization projects (Marinus Link, advanced wastewater reuse, resilient transportation) are fueling durable demand for Jacobs' integrated solutions, expected to drive strong revenue growth across high-priority markets.
- Continued strategic shift toward consulting and technology-driven solutions (notably PA Consulting's double-digit growth and operating margins above 20%) is improving business mix, expanding operating margins, and supporting higher future earnings quality and EPS growth.
- Enhanced capital return strategy, robust cash flows, and margin self-help initiatives (including disciplined cost management and margin improvements) are enabling material share repurchases and dividend growth, directly supporting EPS accretion and overall shareholder value.
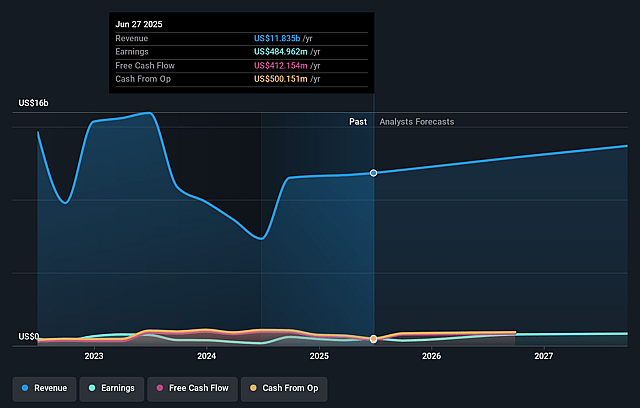
Jacobs Solutions Future Earnings and Revenue Growth
Assumptions
How have these above catalysts been quantified?
- Analysts are assuming Jacobs Solutions's revenue will grow by 7.0% annually over the next 3 years.
- Analysts assume that profit margins will increase from 2.5% today to 6.6% in 3 years time.
- Analysts expect earnings to reach $1.2 billion (and earnings per share of $10.56) by about August 2029, up from $359.3 million today. However, there is some disagreement amongst the analysts with the more bullish ones expecting earnings as high as $1.3 billion.
- In order for the above numbers to justify the price target of the analysts, the company would need to trade at a PE ratio of 19.3x on those 2029 earnings, down from 46.9x today. This future PE is lower than the current PE for the US Professional Services industry at 23.2x.
- Analysts expect the number of shares outstanding to decline by 2.09% per year for the next 3 years.
- To value all of this in today's terms, we will use a discount rate of 7.84%, as per the Simply Wall St company report.
Risks
What could happen that would invalidate this narrative?- Jacobs' ongoing success is partially reliant on robust government and public sector spending, especially in Water, Transportation, and Defense; any shifts in fiscal policy, budget cuts, or political instability (as seen in U.K. infrastructure delays and uncertainty about U.S. federal funding allocations) could introduce revenue volatility and jeopardize long-term backlog and top-line growth.
- Although the company is diversifying and investing in high-growth markets like Data Centers and Life Sciences, these areas can experience rapid technological change and shifting client expectations, potentially requiring large, continual investments in digital solutions and AI capabilities; such capital intensity and the risk of misallocation could compress net margins and strain cash flows if growth slows or competition intensifies.
- Jacobs is benefitting from secular tailwinds like infrastructure modernization and climate adaptation; however, macroeconomic risks such as rising interest rates and tighter credit markets could dampen global infrastructure and capital spending, leading to delayed or canceled projects and adversely impacting both revenue and earnings.
- The company's backlog growth is weighted toward longer-tail Water and Infrastructure projects, which, while providing revenue visibility, may expose Jacobs to project execution risks, cost overruns, and potential regulatory changes over multi-year timeframes-negatively affecting margins or resulting in earnings revisions if not managed effectively.
- Integration and performance risk remain around acquisitions (e.g., PA Consulting) and business separations; any difficulty in extracting anticipated synergies or achieving organizational efficiencies-especially as Jacobs shifts toward higher-value consulting-could result in elevated operating expenses, underperformance in intended margin improvement, and downward pressure on overall earnings.
Valuation
How have all the factors above been brought together to estimate a fair value?
- The analysts have a consensus price target of $161.8 for Jacobs Solutions based on their expectations of its future earnings growth, profit margins and other risk factors.
- However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $181.0, and the most bearish reporting a price target of just $144.0.
- In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $17.4 billion, earnings will come to $1.2 billion, and it would be trading on a PE ratio of 19.3x, assuming you use a discount rate of 7.8%.
- Given the current share price of $144.03, the analyst price target of $161.8 is 11.0% higher.
- We always encourage you to reach your own conclusions though. So sense check these analyst numbers against your own assumptions and expectations based on your understanding of the business and what you believe is probable.
Have other thoughts on Jacobs Solutions?
Create your own narrative on this stock, and estimate its Fair Value using our Valuator tool.
Create NarrativeHow well do narratives help inform your perspective?
Comments
0 commentsDisclaimer
AnalystConsensusTarget is a tool utilizing a Large Language Model (LLM) that ingests data on consensus price targets, forecasted revenue and earnings figures, as well as the transcripts of earnings calls to produce qualitative analysis. The narratives produced by AnalystConsensusTarget are general in nature and are based solely on analyst data and publicly-available material published by the respective companies. These scenarios are not indicative of the company's future performance and are exploratory in nature. Simply Wall St has no position in the company(s) mentioned. Simply Wall St may provide the securities issuer or related entities with website advertising services for a fee, on an arm's length basis. These relationships have no impact on the way we conduct our business, the content we host, or how our content is served to users. The price targets and estimates used are consensus data, and do not constitute a recommendation to buy or sell any stock, and they do not take account of your objectives, or your financial situation. Note that AnalystConsensusTarget's analysis may not factor in the latest price-sensitive company announcements or qualitative material.